Good morning and happy Sunday.
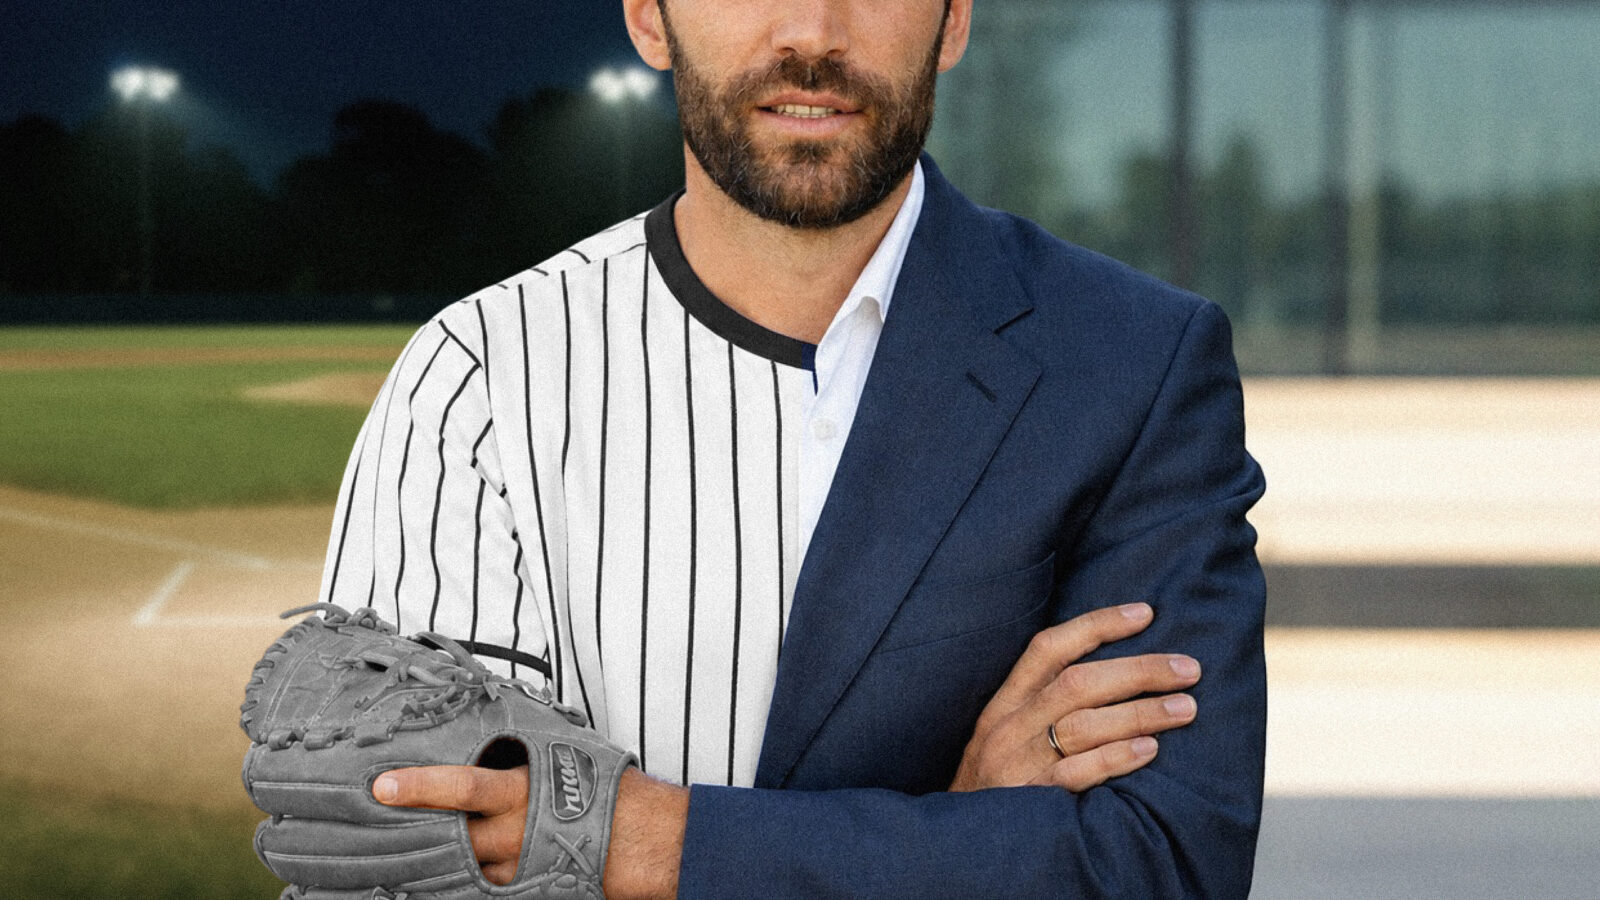
Meaningful work and flexibility are among the top reasons people leave jobs for new careers in financial planning.
But first, a word from our sponsor, Conquest.
A man is only as good as his tools, they say.
But plenty of advisors have been feeling short of a few lately, with 58% saying their financial planning technology is missing key features, functionality, or integrations, per Cerulli research.1
If you’re an RIA, you’ve probably felt the pain this brings first-hand, as you spend hours building a financial plan from scratch for a client. With only so many hours in the day, you’re left having to choose and prioritize which households get your most in-depth work.
While nobody is handing out more hours, Conquest has rebuilt the tooling for the tasks that are eating yours — and they’ve opened a waitlist for independent advisors to gain direct access.
Strategic Advice Manager® (SAM), the firm’s verifiable AI engine, evaluates hundreds of strategies against a client’s actual situation and drafts a personalized plan in minutes, leaving you to then simply decide what to apply.
The Outsiders: Why So Many Financial Planners Are in Their Second Careers
Emily Bandoni was teaching the Pythagorean theorem to a sophomore math class when a student asked her how the geometric principle would ever apply to real life.
“I remember not having an answer,” she said. “That was definitely a moment for me of realizing that I maybe wanted to do something different that would be more helpful for a broader audience.”
“Something different” turned out to be financial planning. After teaching high-school math in Boston for four years, Bandoni now works as a certified financial planner, director and wealth advisor at Gainline Financial Partners.
She is among the 34% of CFP professionals who previously worked in unrelated fields, according to 2023 data from the CFP Board. That aligns with the 2025 Amplified Planning/Schwab Advisor Services research showing nearly 40% of new financial planners are career changers.
About one-third of career changers come from a financially adjacent career, such as banking, insurance and accounting, said Lisa Davis, chief program officer at the CFP Board. Another 40% come from a broader category of public-facing or relationship management industries, which range from sales and marketing to retail and hospitality.
“In some of the programming that we’ve been doing to specifically help career changers transition, we’re seeing just this broad array of careers,” Davis said.
Anyone who has worked to become a CFP knows it’s a rigorous process. Advisors need a bachelor’s degree, coursework in financial planning (either undergraduate or a certification program) and 4,000 to 6,000 hours of experience; they also have to pass an exam and meet an ethics requirement. For July, the CFP Board reported a 66% pass rate.
To help prospective CFPs, the board offers guidance and financial support. Since 2016, it has awarded $3.4 million in scholarships, Davis said.
This year, CFP Board launched its first scholarship focused on career changers, the Cary Carbonaro Women & Wealth Career Changer Scholarship. It awards up to $5,000 per student seeking to complete a certificate-level CFP Board Registered Program and is designed to support the next generation of women financial planners.
Prescription for Change
The primary motivators to choose financial planning as a second career include a sense of purpose, helping people, greater work flexibility and being financially rewarded, Davis said.
Those reasons resonated with second-career CFPs who discussed their transitions with Advisor Upside.
Dr. Bryan Jepson, financial advisor, Targeted Wealth Solutions, transitioned from a 30-year career as an emergency medicine and clinical doctor.
ER doctors have the highest burnout rate in medicine and work nights, weekends and holidays, he said.
“If you’ve seen The Pitt, then you get it instantly,” Jepson said, referring to the HBO Max medical drama set in a Pittsburgh hospital.
He enjoyed making a difference, but he was starting to feel burned out. He had always had an interest in personal finance and investing, and pursued it as a career change over three years ago. While still practicing medicine he received a master’s in finance and then became a CFP. He formally retired from medicine in February.
Juggling a career in medicine while prepping to become a financial planner was challenging, but he loved it. “I found that even though I was busier during the process of starting this new career, I was more energized and less burned out,” he said.
Flexibility was a big motivator for George Herr, wealth advisor with Mercer Advisors. He left a 30-year engineering career at Ford Motor Co. to join the field, in which he had become interested after working with a financial advisor following the 2008 crash.
“My day never ended,” he said, explaining that he collaborated with coworkers and others in Europe and Asia. “When I had a spin class, I tried to do it at 5:30 in the morning. I couldn’t do it. There was a meeting. It was just ridiculous.”
His current job gives him greater flexibility to manage clients’ needs, allowing a more nine-to-five career than what he was used to. Herr started on his own advisory path two years before a planned 2020 retirement from Ford by going to night school to meet CFP education requirements.
‘Daunting’ Effort to Become a CFP
It wasn’t an easy transition, but the financial advisors are happy they did it. Herr, who has two master’s degrees in engineering, admitted some of the course work and exam prep was much harder than he realized it would be.
“It was really daunting. Even as an engineer, it’s totally different,” he said.
Bandoni found financial planning through a friend who was working at Fidelity in the 401(k) division and saw it as a way to combine teaching and her math background. Still, she had a steep learning curve. Being a woman and the only person who didn’t have a finance background was also intimidating at first.
“It was kind of terrifying, actually,” she said.
But coming from different backgrounds gives these advisors a unique insight and connection with clients. Jepson has a niche with physicians, and Herr said his detail-oriented nature as an engineer is a plus.
Basic Training. Mitch Hockenbury, vice president of wealth strategy at Triad Wealth Partners, served in the Marine Corps and Army before becoming a financial advisor. Four years before he retired from the military, he had founded and eventually sold an advisory business.
The desire to help others, discipline, planning and an ability to remain calm in stressful situations that served Hockenbury in the military translated well to financial planning. His job at Triad is to help other advisors, and he is often brought in for advanced planning cases.
“There’s a protector part of me, still,” he said. “I was trained for so many years, so you still feel like you should help people. Protecting could be lives, it could be money.”