Good morning and happy Friday.
It’s that time of year again.
Medicare’s annual open enrollment period starts Oct. 15 and runs through Dec. 7. During the window, everyone eligible for Medicare can join, switch or drop a Medicare Advantage plan (Part C) or a prescription drug plan (Part D), or switch between original Medicare and Medicare Advantage.
Picking a plan is tricky, and in addition to relying on advisors, retirees are increasingly turning to AI to help make Medicare decisions, according to an eHealth survey. More than six in 10 plan to use AI to compare Medicare plans, while 58% say they’ve been targeted by a Medicare-related scam.
One thing everyone should know is that Medicare doesn’t do coldcalls. So if “Medicare” gives your client a ring out of the blue, they should probably just hang up.
Supreme Court May Decide the Future of 401(k) Investment Benchmarks
Of things we consider meaningful in life — community, purpose, personal growth — benchmarks don’t usually come to mind.
But in the world of 401(k)s, meaningful benchmarks are pretty high up there. That was highlighted this week in oral arguments the US Supreme Court heard in a case known as Anderson v. Intel Corporation Investment Policy Committee. The matter arose after employees sued Intel for using a default 401(k) plan investment option that included private assets to hedge against excessive losses. Plaintiffs claimed the fund in question has lagged the S&P 500 and was an imprudent choice. The defense countered that plan administrators didn’t select it to maximize performance and that the plaintiffs’ failure to offer a meaningful benchmark should render their claims moot.
Prior appellate rulings in this and related cases have reached conflicting conclusions about the role of “meaningful benchmarks” in the assessment of fund performance complaints of this nature. Now, the top court could settle the matter.
Intel for Dummies
A Supreme Court decision backing Intel would mean that plaintiffs in some jurisdictions could face a bigger hurdle for claims involving investment underperformance under the Employee Retirement Income Security Act. That seems like the probable outcome based on the tenor of the majority of the justices’ questions during the Tuesday hearing, several attorneys told the Retirement Upside. But that’s far from a guaranteed outcome at this point.
A pro-Intel ruling could spare future defendants from the substantial time and expense of discovery, though the implications for excessive-fee claims will depend on the court’s reasoning and the scope of the decision, said Bonnie Treichel, founder of Endeavor Retirement.
“A more detailed definition of a ‘meaningful benchmark’ would provide greater certainty but could also provide a checklist for plaintiffs’ firms drafting complaints,” Treichel noted. “Remember, as well, that the DOL’s proposed investment selection rule uses ‘meaningful benchmark’ as a criterion in fund selection and review.”
Investor Protection. Regardless of who prevails in the case, one thing is sure. The oversight of retirement plans remains a serious business that involves evolving-but-exacting legal standards and significant responsibility for plan administrators. That’s as it should be, according to Dominick Freda, legal director at Better Markets, which filed briefs in the case supporting the plaintiffs.
“American workers depend on their 401(k)s to retire with dignity,” Freda said. “There should be high standards in place protecting investors. The workers in this case claim that their plan managers gambled with their savings … and then refused to change course despite predictable underperformance. We hope the Supreme Court will agree that those allegations state a plausible ERISA claim, which is enough to let the lawsuit move forward.”
All Your Clients Should Feel This Retirement Certain
Markets shift and rates swing, but retirement timelines do not wait for either to settle, and your clients still expect an answer when they ask if they are on track, this quarter or ten years out.
T. Rowe Price helps you deliver that answer, with more than fifty target date investment professionals digging into how people save and spend instead of leaning on models alone. You get a choice of target date solutions built around your clients’ real-life goals and circumstances.
Backed by two decades shaping retirement futures, T. Rowe Price’s risk approach accounts for the full retirement picture, including the risks and opportunities that surface for your clients at or after the target date.
Don’t Take the ‘Heartbreak Express’ to Estate Disputes
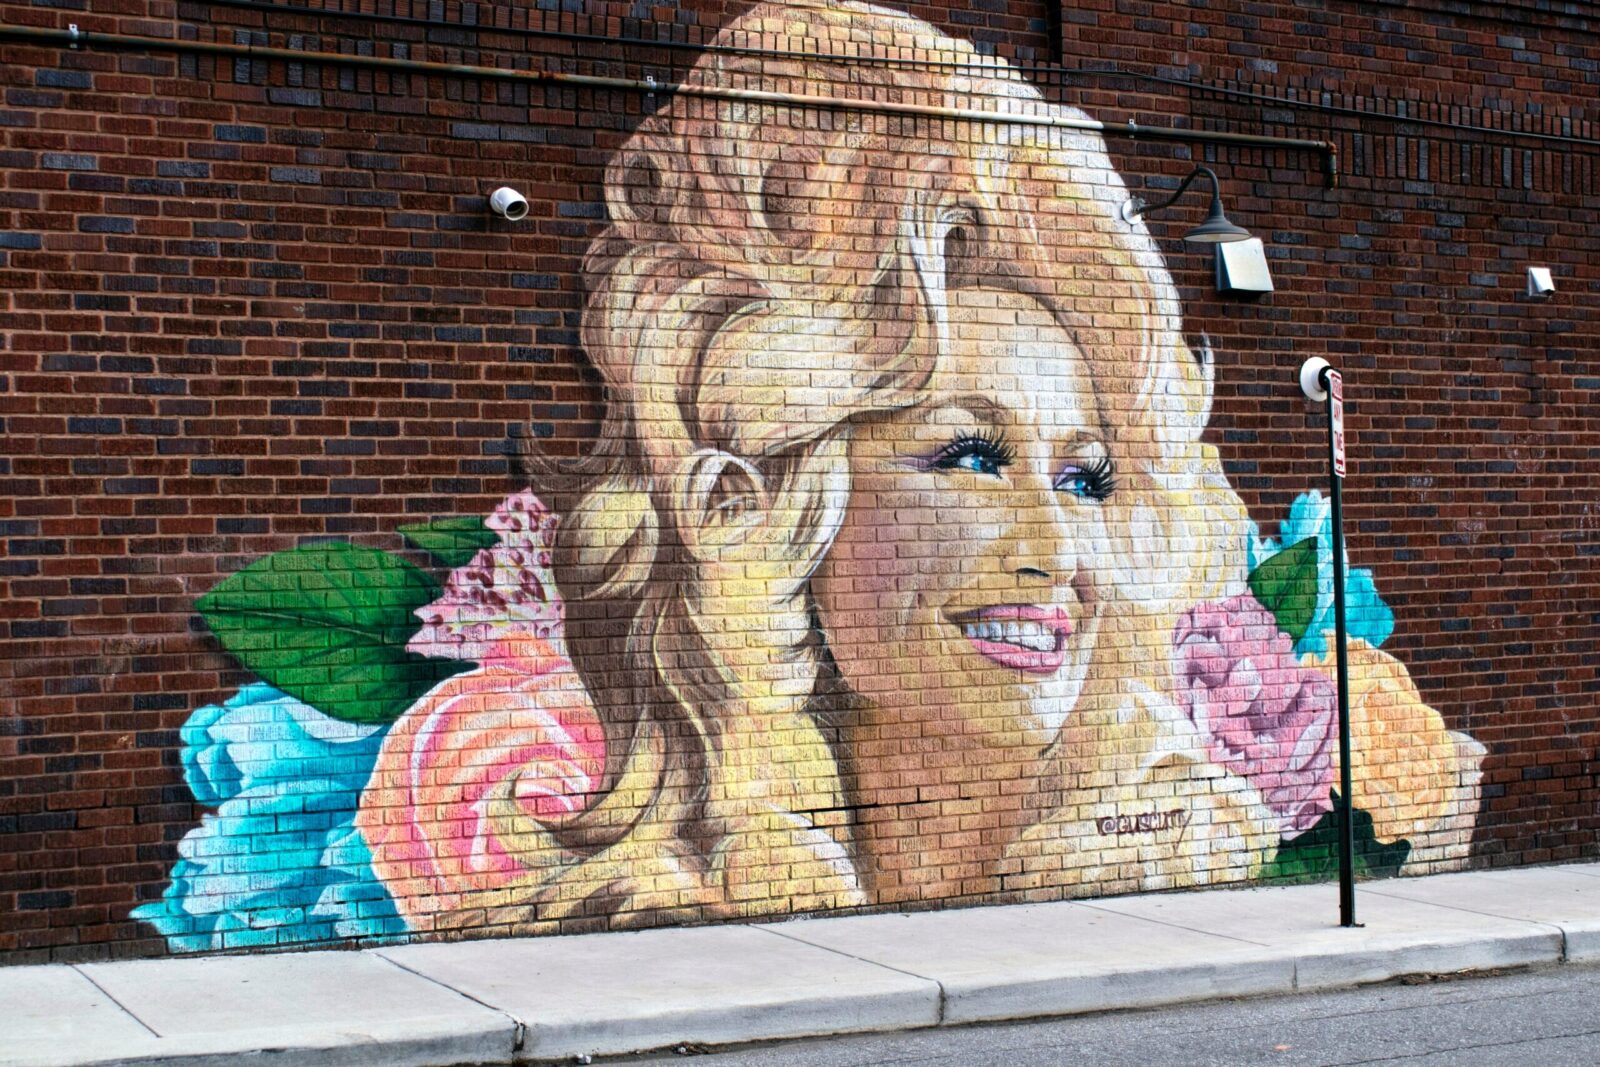
What do Dolly Parton, Jimmy Buffett and Michael Jackson all have in common?
If you said they’re all late chart-topping musicians with millions of devoted fans, you’d be right. There’s something else, less fortunate: ongoing disputes about their estates. Dueling parties with interests in Parton’s estate were in court just this week, in fact, with a judge granting the late singer’s nephew (and former security guard) more time to prepare to defend himself against a restraining order filed by She’s Alive, the entity founded to manage and protect Parton’s assets and intellectual property interests.
While most financial advisors don’t work “9 to 5” for world-famous musicians, there’s still a lot for them to learn from headline-grabbing estate disputes — starting with the fact that not every estate planning dispute is avoidable, said Sean Houghton, director of New Hampshire Shores Trust.
“That’s certainly true, but a solid plan and proactive communications can help prevent the worst outcomes,” he said.
‘More Where that Came From’
While he’s not privy to nonpublic details, Houghton suspects that Parton’s plans are well thought out, and that She’s Alive will be able to maintain control, per her expressly stated wishes.
“Dolly was known for being savvy financially, and she was vocal during her lifetime about wanting this stuff to be buttoned up and not have people fight over her legacy,” Houghton said. “That’s another big lesson in itself for advisors to take away.”
Setting expectations is paramount, especially in cases where there could be some ambiguity, said Jennifer Goode, senior national director of the Wealth Strategies Group at Bernstein Private Wealth Management. Parton died without having had children of her own, for example, which changes the default assumptions about estate planning.
“When people first look for help with estate planning, we find they’re often running away from something, whether that’s a tax bill or worries about how the next generation will behave,” Goode said. “The most effective planning happens when people are running toward something, when they have a vision of what they want to achieve, and Dolly was a great example of that.”
‘It’s All Wrong, But It’s Alright.’ Another lesson to learn from Parton’s legacy is the need to confront our own mortality. “A lot of people will kind of sign documents and then just ignore the estate planning topic for years or even decades because it’s uncomfortable to think about mortality,” Goode said. “Like Dolly, we try to flip that on its head and emphasize the idea of proactively creating clarity about one’s legacy, whether it’s going to charities or the next generation.”
The New Math of Running an RIA. Advisory Services Network’s Trey Prescott joins John Manganaro to talk through the private equity wave that’s swept the RIA industry, how his team keeps pace with the flood of new AI tools, the hidden time costs of running a firm, and why the succession conversation should start early. Plus: his forecast for where the industry heads next.
 Listen to this week’s episode here.