Good morning.
If “three is a magic number,” the figure people have in mind for retirement is practically Hogwarts.
Affluent Americans now say they will need $2.6 million to retire, a figure that has gone up 26% since last year, per a recent HSBC survey. What’s more, savers say they’ve accumulated, on average, just a little more than half of what they’ll need.
We’d love to hear School House Rock’s take on maxing out 401(k) contributions and tips on receiving full retirement benefits.
Election Season May Feel Overwhelming, but It’s Often Business as Usual
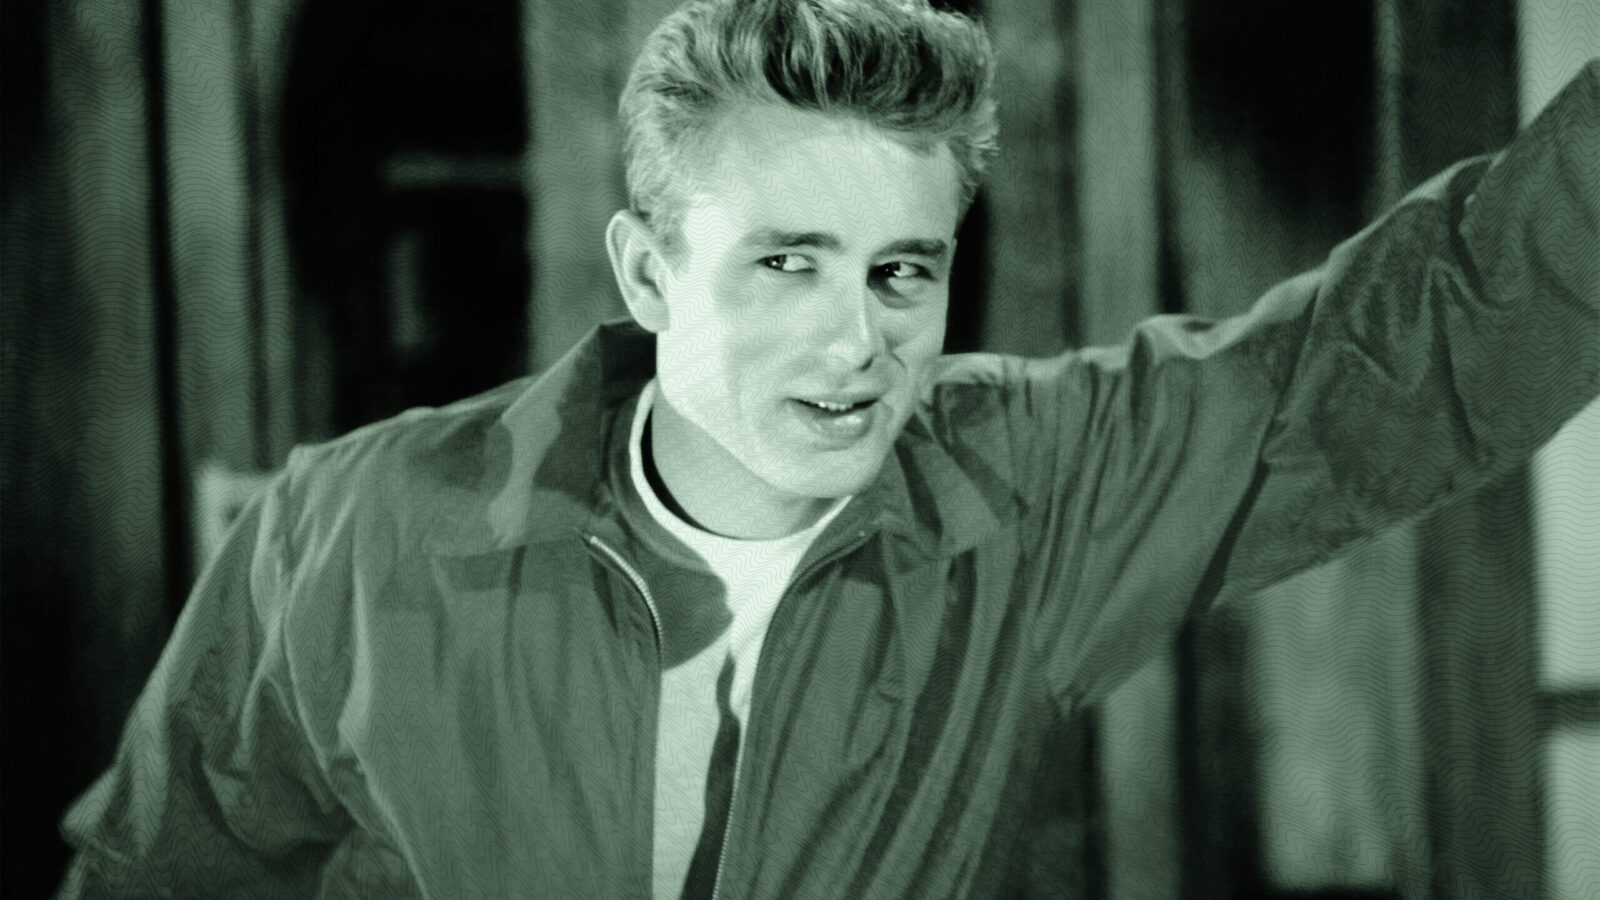
Election season is an emotional and confusing time, best summed up by a famous James Dean line from “Rebel Without a Cause”: “You say one thing, he says another, and everybody changes back again!”
Amid all the political noise, financial advisors are preaching patience. Election outcomes may influence the economy and markets in the short term, but they rarely justify significant changes to long-term investment strategies. Instead, advisors say their job is often to keep clients calm and focused on the bigger picture.
That’s not always easy when Americans are bombarded with political ads, headlines and get-out-the-vote text messages from Ice-T (anybody else getting those?).
Clients sometimes worry that a victory for their political opponents could hurt their finances, but that’s rarely how things play out, said John Power, principal advisor at Power Plans. “Most of my clients have been with me since before the Great Recession and know that time in the market is far more important than trying to guess what the market will do and respond,” he told Advisor Upside.
America Speaks
Though he hates how true it remains, political strategist James Carville’s famous words, “It’s the economy, stupid,” continue to resonate with voters:
- Healthcare costs, the war in Iran, wealth distribution and gas prices are among voters’ top concerns heading into the midterm elections, according to a Gallup poll.
- The share of Democratic voters who consider the economy an extremely important issue has risen to 59%, up from 33% during the 2022 midterms.
- Meanwhile, economic concerns have fallen among Republicans, down from 64% to 39% since 2022.
But while these are legitimate concerns, it’s difficult to predict how changes in the House and Senate will affect the economy, said Juan Hernandez-Ariano, founder of WealthCreate. “I don’t think anyone can tell you what a shift in Congress does to the overall economy,” he told Advisor Upside. “I’d be skeptical of an advisor sending clients a confident call on it this week.”
The More Things Change … Election season or not, clients rarely ask about investments and portfolio construction, with conversations tending to focus instead on their broader financial plans, said Bryan Byrer, founder of Millennial Financial Planning.
“Things are always going on in the world. How is today really any different from when we went into Iraq and Afghanistan?” he told Advisor Upside, adding that financial planning has to remain centered on the individual. “As long as our monetary system stays the same and we don’t fall into fascism or totalitarianism where what the dollar represents shifts, income and spend rates are still going to be what dictates a client’s financial success.”
How Much of Your Week Goes to Client Planning?
The answer usually depends less on the advisor and more on their firm’s operating model.
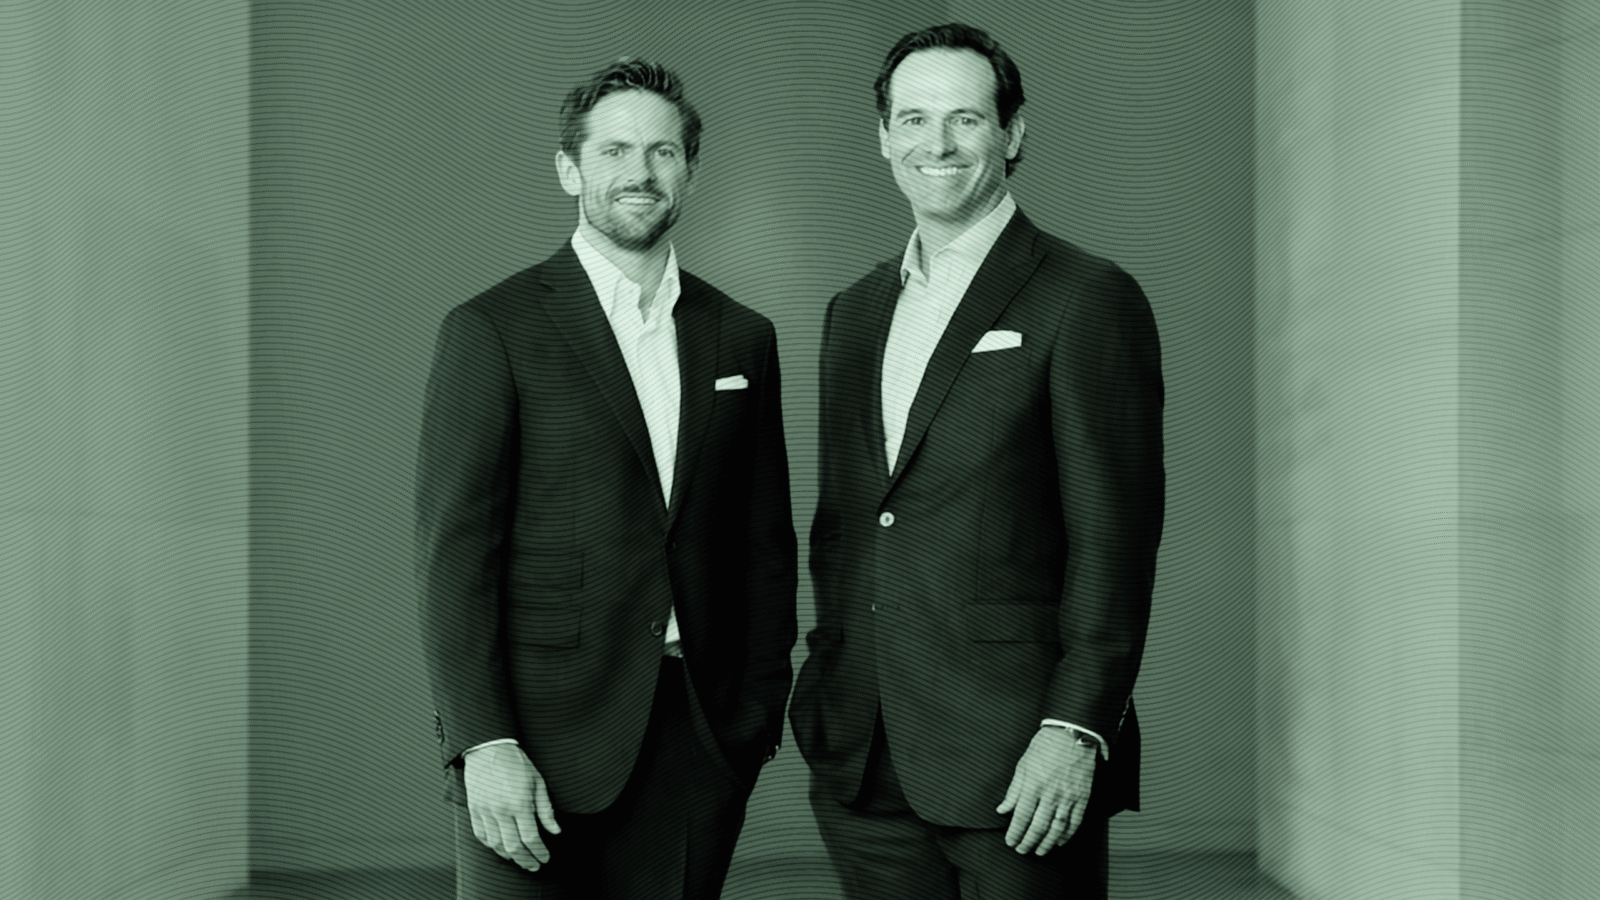
Christian Hutchins and Jesse Brown hit the limits of theirs at a volume-driven firm, so in 2024 they launched Rolling Hills Advisors, and put client-planning at the center.
A consultant pointed them to Mariner Independent, which took on compliance, reporting, and technology selection, while adding mentorship on growth strategy. Staying independent also meant keeping their custody relationship with Fidelity, which made transferring existing client assets easier.
“The custodial relationship was huge, and I don’t think we would have made the move if we had to change it,” says Brown.
This supported independence model gives them room to grow intentionally, true to the vision they started with.
Read more about how a planning-focused culture can be built.
For Investors Who Love, Need, Want Income
If you already use worst-of exposure, the payoff is familiar. The engineering isn’t. Designed to deliver high, monthly income linked to the least-performing of SPY®, QQQ® and IWM®, CAYN: World’s First Indexed Least-Of Autocallable Income ETF brings a familiar autocallable payoff into an innovative ETF structure. See how CAYN works.
Lost and Found: Clients May Have Retirement Wealth Hidden Away
Ready or not, here I come!
We all loved playing hide-and-seek as kids. It’s less fun when it comes to tracking down old retirement accounts.
Left-behind 401(k)s are part and parcel of retirement savings for many of us, with median tenure in the US workforce now standing at 4.1 years, per the Bureau of Labor Statistics. The figure implies a significant number of job changes during the career of the typical worker, who now relies on defined-contribution plans and IRAs to save for retirement. But even financially savvy clients may not realize they have an account from a job they haven’t thought about in years. The dynamic gives advisors an opportunity to deliver better outcomes for forgotten 401(k)s.
“The reality is there are billions of dollars sitting in accounts your clients may not have chosen and don’t know exist,” said Romi Savova, founder and CEO of the retirement account consolidation service PensionBee.
Good Intentions
Beyond the passage of time and the changing of jobs, well-meaning public policy is part of the reason why accounts can get misplaced. These days, many people are automatically enrolled in a retirement account at their new employer. That’s a great thing, Savova said, but if they don’t stick around long and save less than $7,000 before departing for yet another new job, the account can be automatically swept out of the plan and into a rollover IRA. That adds a layer of complexity to any future search for left-behind accounts. Automatic rollover IRAs are on track to grow from more than $20 billion today to $43 billion by 2030, Savova said.
Research published by Empower in October backs that assessment:
- More than a third (34%) of Americans said they may have lost track of old retirement savings.
- The figure rises to half of Gen Z and 45% of millennials.
The research suggests shorter-term financial priorities like paying monthly bills and managing debt take precedence over keeping tabs on old retirement accounts. Likewise, finding an old account that has been swept to an IRA provider only solves part of the problem. These accounts often start losing value thanks to a combination of high account-opening fees, monthly maintenance costs and allocations to cash or low-risk investments, so taking some action is often warranted, Savova said.
Support from Uncle Sam. A resource for retirement savers searching for old accounts is the Retirement Savings Lost and Found Database created by the Department of Labor’s Employee Benefits Security Administration. It was established as part of the Secure 2.0 Act of 2022 and serves as a hub to find lost or forgotten benefits, including both defined-pensions and defined-contribution accounts like 401(k)s.