Good morning.
Hey, Chuck.
Discount brokerages like Robinhood, Webull and Interactive Brokers have introduced AI to their retail platforms, and now Charles Schwab is throwing its digital hat in the ring.
The firm is set to debut its AI assistant, “Charley,” to eligible retail clients later this month. Through text or voice chat, users can ask Charley for help with portfolio construction, finding account information, updating financial documents and connecting with Schwab reps. Demand for the technology appears strong. In a recent Schwab survey, roughly two-thirds of retail investors said AI can either help execute routine tasks or play a meaningful role in investing when paired with human expertise.
We remember when people hated these digital assistants. Microsoft’s Clippy, we hardly knew ye.
Add 20+ Years of Bond Expertise to Your Allocations
With rates elevated and economic and credit conditions evolving, fixed income offers a broad range of opportunities across sectors. These conditions may create opportunities for active management. Dispersion across sectors, issuers and securities can drive meaningful differences in risk and return, creating opportunities for experienced managers who seek to add value through security selection, sector allocation and risk management.
Specialized expertise can help investors navigate opportunities across fixed income markets. New York Life Investment Management brings extensive capabilities across municipals, high yield, securitized credit and global bonds. Our dedicated teams average more than 20 years of portfolio management experience and collectively manage $332 billion in public fixed income assets.1
Explore fixed income portfolios with the specialists at New York Life Investment Management.*
This Week’s Highlights
Why the Treasury Is Cracking Down on 351 Conversion ETFs
The latest tax-management fad is getting a reality check.
ETF investors have increasingly taken advantage of Section 351 of the US tax code over the past several years, allowing them to move appreciated assets into a new vehicle without immediately paying capital gains taxes (provided the new fund meets certain requirements).
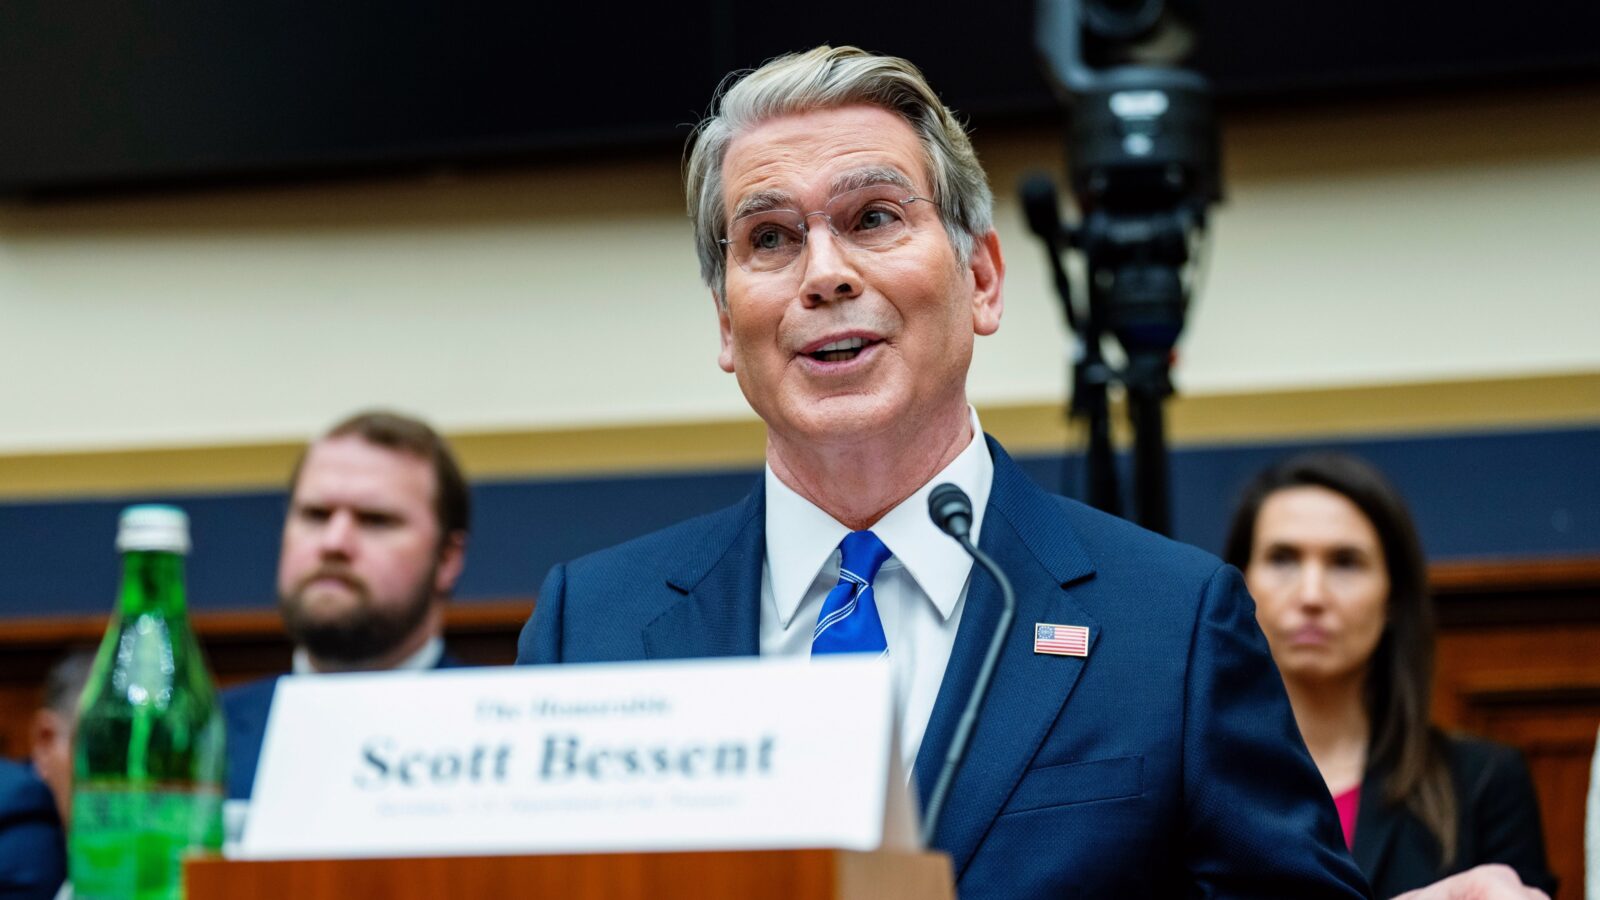
Now, the Treasury may finally be taking aim at certain so-called “351 conversions” that it says don’t jibe with tax law. The department on Monday limited one such transaction involving an ETF and flagged several others. The move signaled the government’s willingness to crack down on some of the funds that fall into this category.
“Investors purportedly avoid recognition of the built-in gains in their securities while effectively exchanging those securities for an indirect interest in an ETF with a materially different portfolio,” the Treasury’s statement reads. “In these transactions, [Sections] 351, 721 and 852(b)(6) are being applied … to achieve a result that these provisions were not intended to produce.”
Laying Down the Law
The Treasury had previously signaled its disapproval of 351 conversions — officials called them “too good to be true” at a recent industry event — but until now, no regulatory actions had been taken. Funds that use the strategy now number over 120, with more than half of those launching in the past year alone. Guidance on the subject was much-needed, said Shang Chou, co-founder of the multi-family office Dishmi Capital. “This is a positive thing. There are now clear[er] guidelines on where investors should be standing,” he said. “Going in there with a plan to skirt out on the capital gains tax to get diversification with this pre-planned idea to dispose of those assets — that’s going to be a no-go going forward.” That said, the department’s language seems to leave a window for what Chou called “well-behaved 351s” — that is, funds that make use of assets already aligned with the ETF’s core strategy.
The trend is real: The MIG Core ETF, for example, took assets from the Hot Pocket empire earlier this year and put them into the ETF structure. “I would contrast that with ETF firms looking to launch S&P 500-tracking ETFs and willing to take in diversified baskets,” Chou said.
Not Over Yet: The underlying principle behind the Internal Revenue Service’s actions is economic substance over tax gains, Chou said. “You shouldn’t be contorting your balance sheet in weird ways just to avoid or defer taxes. That makes no sense,” he added.
The government will also seek public comment on the transactions it targeted, as well as asking about others that it said should be regulated similarly, with the comment period closing at the end of October.
Appetite for US Bonds as Safe Haven Rebounds After Global Yields Spike
There are bond markets outside of the US so frightening they make America look superlative by comparison. US Treasuries rebounded from an early sell-off Thursday, as decades-high yields on long-term government debt tempted an influx of buyers. Meanwhile, the allure of US government debt is strengthening with some money managers and retail investors, and traders signaled Thursday that they think Uncle Sam could provide safe haven from bond market tumult brewing elsewhere.
Give Them a 60-40 Chance
The yield on the 10-year Treasury note finished September with the biggest quarterly gain since 1994 and reached a 24-year high of 5.34% early Thursday. However, buyers quickly came calling after the initial selloff and the yield closed the day at 5.233%. A handful of supporting developments coalesced around their purchases.
First, a new Institute for Supply Management report revealed that economic activity in the US manufacturing sector grew slower than expected in September. Cooling in the white-hot American economy could give the Federal Reserve cause to hold off on additional interest rate hikes, which would steady the value of Treasuries. Fed Vice Chairs Philip Jefferson and Michelle Bowman offered support for that narrative, suggesting policymakers had more wiggle room. Any delay in hikes would mean less short-term upward pressure on yields from Fed policy.
Second, the global bond selloff reminded markets that US Treasuries are actually a safe haven. Look no further than France, where belt-tightening measures introduced in Prime Minister Sébastien Lecornu’s latest budget on Thursday failed to ease the market’s concerns about ballooning deficits and a deteriorating fiscal outlook. The spread between 10-year government bond yields in France and Germany reached the widest since the euro area’s early 2010s sovereign debt crisis. With global economic uncertainty piling up, investors expressed a preference for US and German bonds, which are viewed as relatively risk-free. Against the backdrop of higher Treasury payouts, there’s also evidence more and more corners of the market are reassessing bonds:
- The Wall Street Journal reported earlier this week that money managers are telling their clients to jump back into Treasuries and reawaken the classic 60-40 portfolio, arguing the high yields and cheap prices on long-term bonds are too sweet to miss out on. Halbert Hargrave Co-Chief Investment Officer Brian Spinelli told the paper “the biggest challenge is going to be psychological,” referring to investors still associating bonds with the near zero interest rate environment of the Covid era.
- A significant number of retail investors have gotten the message. JPMorgan noted in its latest weekly retail activity note that the iShares 20+Year Treasury bond ETF saw its largest inflows ever, indicating the 30-year bond yield is in the sweet spot as far as the new rush of retail traders are concerned.
Home Evasion: Everything else aside, the turbulent waves caused by bond market mayhem are making potential homebuyers seasick. The average 30-year fixed-rate mortgage rate rose the most in four years this week to 7.28%, according to Freddie Mac data released on Thursday.
- AI’s cash-flow test: A lesson from the GFC. Read the insight.
- Calculate your book’s market value in four minutes. Start here.
Legacy Planning Can Get a Little Awkward. That’s OK
“To be cringe is to be free,” as the internet’s modern philosophers have proclaimed.
In that vein, great wealth brings great opportunity for families to enjoy life, give back to their communities and empower future generations — though it can also bring awkward conversations.
That’s because the written estate plan is only part of a successful intergenerational wealth transfer, according to Jesica Ray, senior lead advisor at Brighton Jones Wealth Management. Beyond drafting legal documents and trusts, families need to prepare heirs psychologically to manage wealth. This is best done gradually, through two-way conversations that set expectations. And it pays to start the estate-planning process early, make updates and plan for emergencies.
“People often ask me how long it will take to put an estate plan together,” Ray told Retirement Upside. “That’s not the right way to look at it. It’s an ongoing process.”
That’s a Bit Awkward
Any number of topics can make planning feel awkward or downright uncomfortable. Ray recently wrote an analysis about wealthy parents discussing prenuptial agreements with their heirs, for example. Parents want to celebrate their children’s joy and welcome a new person into the family, of course, but they may wonder what a marriage means for the family’s finances, especially in cases where the heir is expected to take over a valuable family business or inherit a very large amount of money.
“No one plans on watching their home go up in flames, yet we carry homeowners’ insurance,” Ray wrote. “You can position a prenuptial agreement as a type of marriage insurance. It’s not a prediction of failure. It’s more a layer of protection in case things go wrong.”
For families with businesses or significant assets, simply deciding who inherits what may not be enough, said Sean Houghton, director of personal trust services at New Hampshire Shores Trust. In these situations, an effective estate plan:
- Helps distinguish beneficial ownership from decision-making authority, while establishing clear fiduciary roles and addressing what happens when a family member’s professional role changes or ends.
- Creates mechanisms for resolving conflicts before they threaten the assets or family relationships.
Financial advisors can show their value by initiating and normalizing such discussions, Houghton said. The same is true when it comes to parents discussing inheritances with their children, some of whom may be better suited for receiving wealth directly, while others may require more structure and support.
No ‘Trust Reveal’ Parties. Another idea for advisors to bring to the table is dispelling the idea of a “trust reveal” meeting, where heirs learn for the first time what they will (or won’t) inherit. Such scenes make for great television because they dramatize a highly private and vulnerable moment for a family. In real life, a surprise inheritance meeting more often signals that important conversations were postponed for too long.
What Are Buyers Looking For? Elevation Point CEO Jim Dickson joins John Manganaro to walk through a buyer’s RIA diligence checklist, from a repeatable growth process and succession plan to tech that plugs cleanly into an acquirer’s systems. Plus: what a longtime Merrill Lynch veteran learned about going from advisor to CEO, and why he still calls his mentors.
 Listen to this week’s episode here.
Edited by Emile Hallez. Written by Griffin Kelly, John Manganaro, Lilly Riddle, and Quinn Waller.
Advisor Upside is a publication of The Daily Upside. For any questions or comments, feel free to contact us at advisor@thedailyupside.com.
Disclaimer
*Important Disclosure: Active management strategies typically have higher fees than passive management. There is no assurance that active management will achieve investment objectives. Investing involves risk, including possible loss of principal. Fixed income investments are subject to interest rate, credit and market risks; certain sectors may involve additional risks. “New York Life Investment Management” is the brand name and service mark used to represent a group of affiliated investment advisors of New York Life Insurance Company, including New York Life Investment Management LLC, a registered investment advisor.
1As of 3/31/26.