Good morning. Welcome to a special edition of Retirement Upside.
People generally understand that inflation is a challenge in retirement, but they often underestimate its long-term effects, according to Fidelity data. Even a moderate 3% annual inflation rate roughly doubles the cost of goods and services over 25 years, and today, we’re sitting at closer to 4% inflation.
There’s an upside to higher inflation, though, and it comes in the form of higher interest rates. Retirees with high-yield savings accounts, money market accounts and short-term certificates of deposit (CDs) are earning significantly better returns on their money today than in the recent past. For near-retirees looking to purchase an annuity, higher rates also allow insurance companies to offer larger monthly income streams.
Still, it’s important to keep an eye on the cost of living, and it’s probably worthwhile to save a little more today to prevent shortfalls in the future.
Practical Magic: How to Conjure Estate Planning Conversations This Season
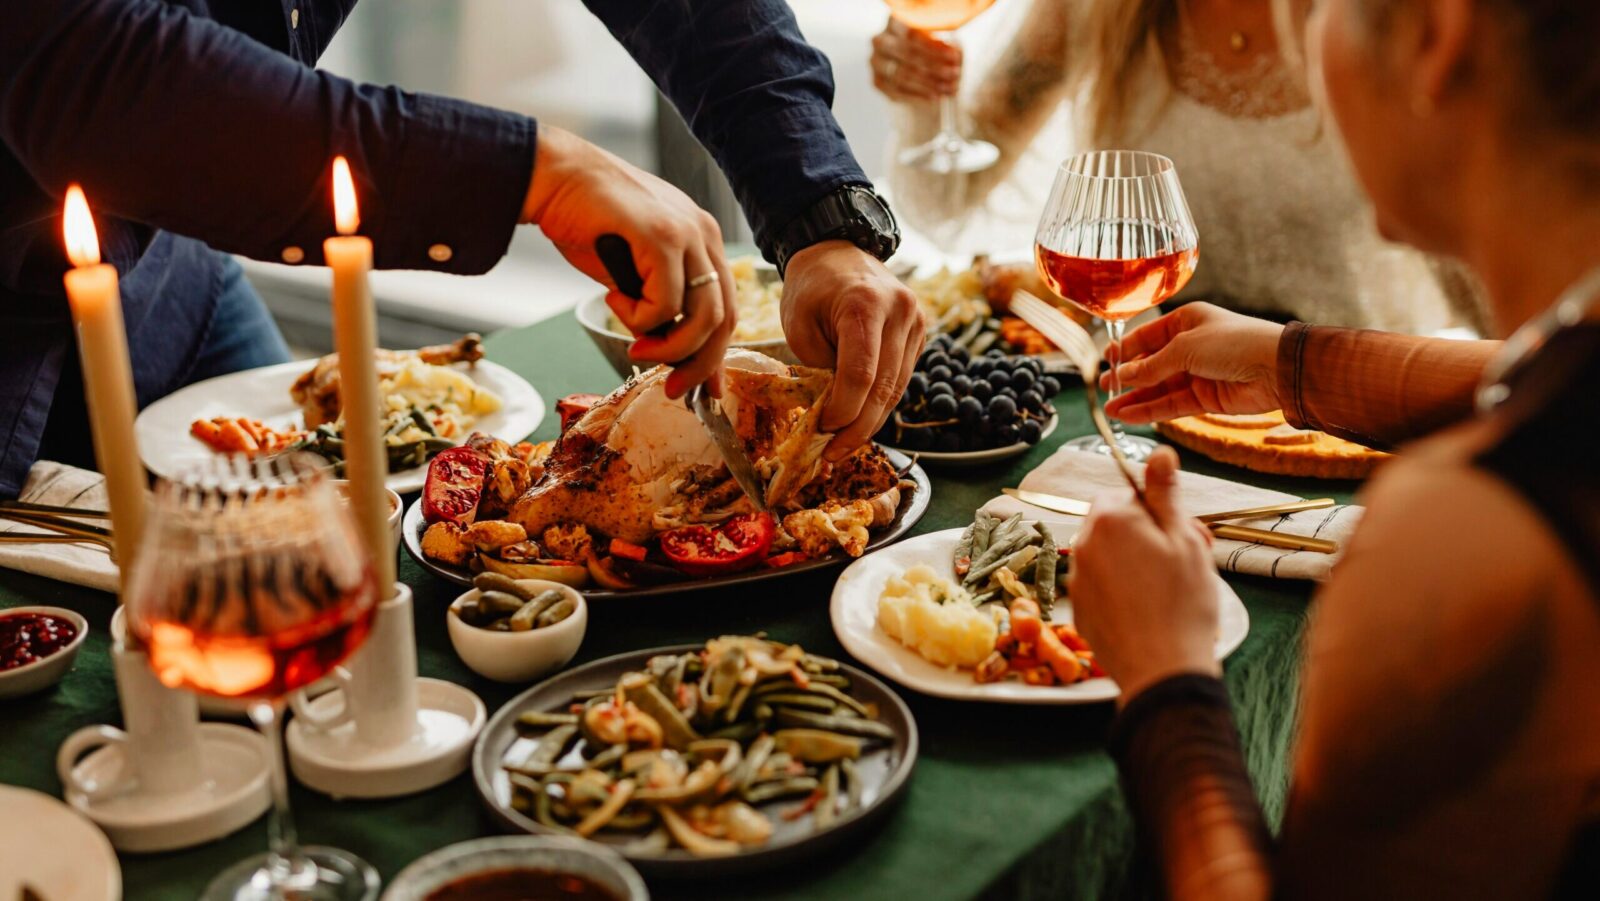
When it comes to politics and religion at the Thanksgiving dinner table, ‘tis often the season to change the subject. But there’s one taboo topic that many people may want to broach when the family gets together this holiday season: money. Or more specifically, what happens to it when the older generation passes on.
Despite the fact that an estimated $124 trillion is expected to change hands through 2048, 56% of adults in the US have no estate planning documents, such as trusts, wills and medical and financial powers of attorney, according to Trust & Will’s 2026 estate planning report earlier this year. So while families may not actually want to get into the nitty gritty of legacy planning and wealth transfer over the turkey and mashed potatoes, it is important for them to spend some time on the books to chat through what comes next. And financial advisors can offer tips to start the conversations.
“Estate planning is one of the most important topics but one of the least talked about,” said Michael Walstedt, founder of Reliant Wealth Advisory.
It’s Not Personal
Even though a successful estate planning conversation may result in paperwork, that’s not where to start:
- “Instead of asking, ‘Do you have a will?’ try sharing your own experience first,” said Corinna Rose, paraplanner at Bell Investment Advisors. That could look like explaining how straightforward making a will was for the person initiating the conversation. “People tend to be much more receptive when they feel invited into a conversation rather than interrogated.”
- Because money conversations can get emotional quickly, it’s best to keep conversations practical, not personal, Walstedt said. He advises clients to start with discussing where various assets are located as opposed to who is getting what.
- Rose said she advises families to remember that estate planning isn’t about preparing for death. “It’s about making life easier for the people you love.”
A New Tradition. Estate planning laws and family circumstances can change over time, so just because a plan is in place doesn’t mean a family can forget it until they need it. “If it has been more than five years since you last reviewed your documents, or you’ve moved to another state, it may be time to revisit your estate plan to make sure it still reflects your wishes,” said Michael DeMassa, founder of Forza Wealth Management.
Retirement Investing Across Public and Private Markets
Many retirement portfolios are diversified, but primarily through public markets.
When public markets experience periods of volatility, asset classes may become more correlated. For retirement investors with long time horizons, some may consider whether additional sources of exposure could complement a traditional portfolio.
The new T. Rowe Price Goldman Sachs Retirement Blend Plus Trusts widen the base. By combining private equity, private credit, and private infrastructure with public markets in a single target date vehicle, they are designed to give clients return drivers that do not all move in lockstep.
Each trust spreads across hundreds of global securities, with risk assessed across the whole mix, not in isolation. So you can speak to the portfolio’s risk as a whole, rather than defending it piece by piece.
Diversification Beyond Asset Allocation: Account Types Matter
To convert or not to convert? That is the question.
The next few months are a good time for clients to ask whether converting some of their pretax retirement assets to a Roth account makes sense, now that most people have a sense of what their total income for 2026 will be. It’s also a good time to educate them about how Roth conversions can affect other aspects of their financial plan, especially future required minimum distributions and what heirs will eventually inherit.
“For investors with larger traditional IRA or 401(k) balances, the most effective Roth conversion decisions come from projecting several years into the future,” said Heather Rivas, wealth advisor at River Wealth Advisors. “It also requires a discussion about whether choosing to pay additional taxes today will pay off in the future.”
Another Kind of Diversification
Most retirement investors are familiar with diversification across different asset classes, industries and geographic regions. Fewer are focused on tax diversification, Rivas said, which is where an advisor can shine.
“Converting to a Roth reduces the balance that will eventually be subject to RMDs,” Rivas said. “That can help retirees avoid being forced to recognize more taxable income than they need in a given year. IRAs are also a very tax-inefficient way to pass money to heirs.”
Any converted assets are counted as income, of course, so converting enough to fill a lower tax bracket may be attractive. However, converting additional dollars could push income into a substantially higher bracket or trigger other costs.
These dynamics make the period after a client retires but before they claim Social Security an opportune time to convert assets at comparatively low tax rates. Some additional considerations:
- A large conversion can increase modified adjusted gross income, potentially triggering higher Medicare premiums and surcharges.
- A conversion may be less attractive if a retiree lives in a relatively high-tax state today but expects to move to a lower-tax state later.
Triple Threat. Funding a Health Savings Account is another way to add tax diversification to the overall plan, said Kimberly Lankford, a longtime AARP contributor and current reporter for The Wall Street Journal Buy Side. The HSA complements other retirement accounts with its unique ability to pay for medical care on a tax-free basis, including Medicare premiums and out-of-pocket costs, she told Advisor Upside. Clients can even move money directly from a Roth or traditional IRA to their HSA through a one-time direct transfer called a qualified HSA funding distribution, though the amount is subject to the annual HSA contribution limit and other eligibility rules.