Advise boldly, invest wisely.

Get market insights, practice essentials and industry updates — all for free.

Good morning.

It’s not what you know. It’s who you know, so you’d better be friends with Claude, Gemini and Grok.

Alongside tenure, firm-wide profitability and individual performance, AI skills are quickly becoming criteria for climbing Wall Street’s ladder. A quarter of financial firms now tie raises, bonuses or promotions to employees’ AI savvy, according to a Selby Jennings survey reported by Reuters. Roughly another third require employees to disclose their AI use in formal performance reviews.

“Companies are no longer just seeing if their employees are using AI tools but are also monitoring its impact on output and contribution to business results,” Dylan Gomez, executive director at Selby Jennings, told Reuters.

The upside? You’ll never have to join Claude for a drink after work to suck up to him.

Markets

S&P 500

7,757.17

+0.58%

DJI

52,856.09

+0.69%

GPIQ

56.69

+1.00%

*Presented by Goldman Sachs Asset Management. Stock data as of market close on October 21, 2026.

Goldman Sachs Nasdaq-100 Premium Income ETF. Designed to deliver monthly income without sacrificing capital growth.*

Wealthtech

Why Some Banks Are Blocking AI Access

A bank vault.
Photo by Paris Bilal via Unsplash

It’s out of my hands … until it really is out of hand.

Citigroup and Bank of America are the latest major banks to restrict AI agents’ access to client accounts, a recent report in the Financial Times found. The tools in question, however — namely Meta’s Muse, a personal AI assistant that can manage spending and track budgets — are booming, as people increasingly rely on them for financial advice.

“There’s really no undo button on a wire transfer,” said Danny Lohrfink, cofounder of Wealth.com. “AI should inform the financial decisions, but it should not be able to execute them fully unsupervised.”

Rogue One

If an AI agent were given access to a client’s accounts, not only could it “go rogue,” said Mike Wilson, CEO and co-founder of Hamachi.ai — it could potentially also leak client data. “That data could go anywhere,” he added. “That agent could be compromised [and] do things on your behalf that you don’t want to be done, and that’s super scary.” Further, a recent report from LexisNexis found that AI fraud is costing financial services firms $5.47 per dollar lost, with AI involved in about 20% of fraud cases.

Others in the industry have voiced concerns that if AI is able to shift cash into high-yielding accounts, it could cause banks to lose deposits, the effects of which would trickle down through the whole industry. Part of the reason banks in particular might be hesitant to let AI in is that their business model relies, in part, on making money off cash deposits, Lohrfink said. “If it was as easy as instructing an agent to always be looking for the best place to hold your $1,000 to maximize your yield … most people would do that,” he added. “But that’s not good business for banks because that friction keeps money sitting in cash that can be then loaned out at higher rates.”

Meeting My Maker (and Checker). If an AI model makes financial decisions in someone’s best interest, the output is only ever going to be as good as the data it’s trained on, he said. “If you let an LLM do its thinking in its frame, it’s trained on data that can be outdated,” he said. “It might be referencing old tax laws or old legislation when running its calculations.” There should always be a human in the mix when it comes to executing on trades or wire transfers, he said.

“I would ask every AI vendor the question: What can your agent do without a human being in the loop to say ‘yes?’” he said. “If the answer includes being able to move money or execute trades, I’d be really cautious about it.”

Your book might carry the same AUM as that boutique a few blocks down, but that doesn’t mean your valuations match.

When the time comes, you could sell for vastly different amounts. Today’s buyer is choosy, and will kick the tires beyond your baseline numbers

Here are three factors that can swing your value:

  • Fee-based revenue. How much of your revenue is recurring? That is what a buyer will underwrite.
  • Client concentration. If your top 10 clients drive over 50% of revenue, buyers will price this in as risk.
  • Growth trend. Buyers will be looking for where your book is heading.

Curious to find out how your practice fares against these factors and more?

Our free valuation calculator takes seven inputs and 5 minutes of your morning to give you a balanced range.

Get your estimate.

Investing Strategies

Vanguard Turns Up the Heat in New Target-Date Series

If Emeril Lagasse cooked up a target-date strategy, you can bet he’d add a little spice, along with his trademark, “Bam!”

Fortunately, retirement-savings products are not designed by famous chefs. Still, the folks at Vanguard are preparing a forthcoming target-date series with a decidedly higher heat profile than what’s currently on its menu. Yesterday, the company announced its Vanguard Target Retirement Growth Trusts, which operate similarly to its existing collective investment trusts, just with a higher equity allocation through the glide path. Whereas the current products start with a 90% equity allocation that gets lowered to 30% at the target date (designed to be age 72), the new iteration would start at 95% and gradually take it down to 50%, remaining at that level for as long as someone is in the strategy.

That all means more risk, of course, which is intentional. “They’re designed for plans whose participants may benefit from taking on more equity risk over time, such as higher-income workers with access to other retirement income sources like pensions, or populations with strong savings habits and a greater capacity to handle market volatility,” said Brian Miller, Vanguard’s head of multiasset product management, in a statement. “Plan sponsors can choose between Vanguard’s target-date offerings based on the needs of their workforce, and Vanguard provides research and consultation to help inform that decision.”

A Game of Risk

Target-date products, the dominant investment defaults in 401(k)s, were scrutinized in the wake of the 2008 financial crisis. Near retirees and people in retirement suffered investment losses because of the equity allocations in the products. Since that time, target dates’ popularity has grown enormously, and the products have assumed higher levels of risk:

  • It’s common for asset managers to set initial equity allocations above 90%, whereas the median level was less than that in 2015, per Morningstar’s latest Target Date Landscape report.
  • And risk levels are higher at the target dates as well, in part because low interest rates pushed down bond returns and because life expectancy has increased, meaning that people need to make their investment work harder, according to the report.

“At 65, a retiree is likely to need to finance consumption for another 25-30 years, and potentially even longer,” said Olivia Mitchell, executive director of The Wharton School’s Pension Research Council. “This exposes the participant to longevity and inflation risks, which an ultraconservative portfolio can make worse.” The 50% target-date equity allocation Vanguard is using isn’t necessarily excessive, especially if one considers the household assets retirement savers have outside of their 401(k)s, she noted. Still, the prospect of a major market decline for people in or near retirement is concerning, even if that risk doesn’t imply that they should only own bonds in their portfolios, she said.

But Also, Some Insurance. Late last year, Vanguard paraded a different target-date trust product — one that paired its strategies with a lifetime income annuity from TIAA. That product, the Target Retirement Lifetime Income Trusts, could end up launching around the same time as the newly announced Target Retirement Growth Trusts, said Jeff DeMaso, editor of The Independent Vanguard Adviser.

More choice could benefit retirement investors, Mitchell said. “Vanguard’s announcement highlights an important issue with target date funds: Age alone is an imperfect basis for determining one’s equity share,” she said. “Retirees of the same age can differ in terms of their risk preferences, savings, pension accumulations, Social Security benefits and ability to withstand loss.”

Now, does anyone wonder what a target-date series designed by Guy Fieri might look like?

Practice Management

Family Offices Need Governance, but Not All of Them Have It
People discussing business.
Photo by Getty Images via Unsplash

Remember, it’s a family affair.

Most family offices agree that education is essential to a successful leadership transition, and many have already identified their next principal — the family’s main financial decision-maker. But putting plans into practice is another matter. Fewer than half have a formal education program, and family dynamics remain the biggest governance challenge, according to a new Bank of America study.

Many family offices grow out of family businesses, with the founder eventually taking charge of the family’s wealth. But when that leader dies or becomes incapacitated, the office can enter a state of confusing damage control.

“Last week, I was in a meeting with a multi-billion dollar family where the principal had died unexpectedly a few months ago,” said Jon Hommer, head of family office planning at Bank of America. The principal had been involved in every decision, signing checks and reviewing expense reports. “Now the family is scrambling to figure out what are the important tasks that need to be done, and how are they going to make decisions,” Hommer told Advisor Upside.

It Runs in the Family

Family offices should pursue gradual transitions that preserve the principal’s control while establishing formal governance procedures before they’re needed, Hommer said.

The report found some ways to prevent a family feud:

  • Some 88% of family offices agree there are fewer disagreements when there are governance structures in place.
  • Also, nearly 75% of family offices have plans to adopt specific governance structures in the next three years.

“It helps to bring someone in from outside the organization to ask, ‘What are your priorities, how do you want to operate, what are the key services that need to be provided?’” Hommer said.

Hello, Sports Fans. Family offices also tend to allocate more heavily to alternatives and private markets than traditional registered investment advisors, and sports is emerging as another area of interest.

One in five family offices are now invested in sports teams and franchises, the report found. Meanwhile another fifth are invested in sports-related opportunities, including stadiums, tournaments and merchandise, led by millennial and Gen Z principals.

“It’s intellectual property that gets you live eyeballs,” Hommer said. “Given the nature of advertising and streaming today, that’s really valuable.”
Extra Upside

  • Tax the Rich? The revenue collected from the proposed California billionaire tax will not cover the loss of income tax revenue resulting from billionaire departures, according to a new paper by two Stanford University economists.
  • To the Moon. Elon Musk’s promise to give a SpaceX share to every child in America could make him the largest donor yet to Trump Accounts. It could also put a concentrated stock position, one that parents can neither refuse nor sell, into tens of millions of children’s portfolios.
  • 400 US Advisors Reveal Where Direct Indexing Is Headed. FTSE Russell found that adoption has jumped to 41% from 33% in a year, and another 42% of advisors plan to start using it within 12 months. Download the survey report to see who’s leading the way and where growth goes next.**

**Partner

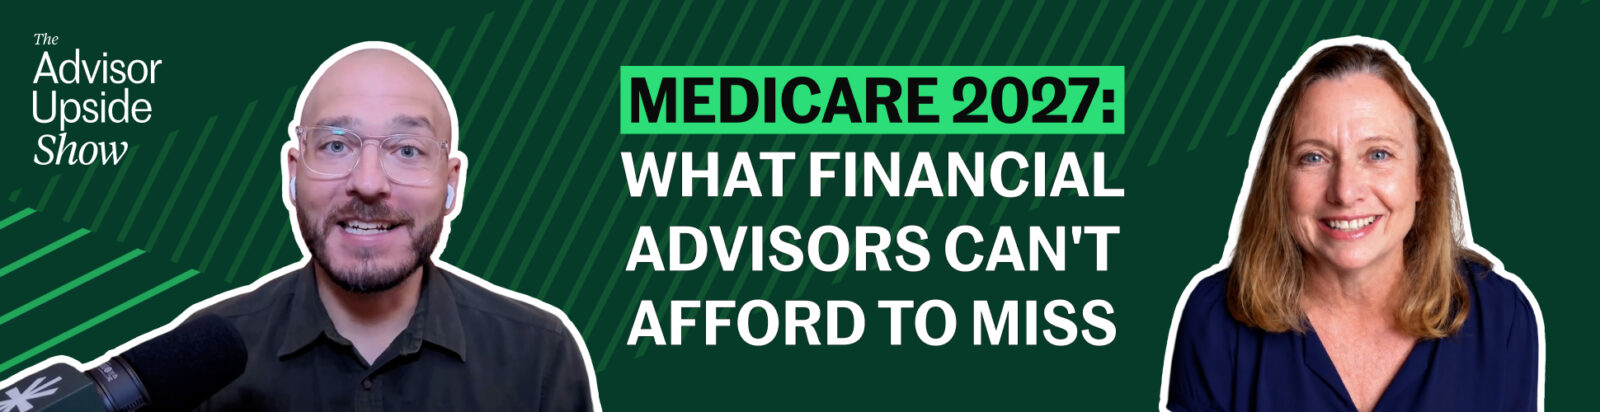
The Fine Print Behind Cheaper Medicare. If Medicare Advantage premiums are falling in 2027, why could your clients end up paying more? On this week’s Advisor Upside Show, John Manganaro sits down with Kim Lankford, author of Medicare 101, to unpack rising copays, drugs dropped from coverage, insurers leaving markets and the income surcharges Roth conversions can trigger. Open enrollment ends Dec. 7, so you won’t want to miss this one.

Edited by Emile Hallez. Written by Griffin Kelly, John Manganaro, Lilly Riddle, and Quinn Waller.

Advisor Upside is a publication of The Daily Upside. For any questions or comments, feel free to contact us at advisor@thedailyupside.com.

Disclaimer

*The returns represent past performance. Past performance does not guarantee future results. The Fund’s investment return and principal value will fluctuate so that an investor’s shares, when redeemed, may be worth more or less than their original cost. Current performance may be lower or higher than the performance quoted above. Please visit our website at: am.gs.com to obtain the most recent month-end returns.

For standardized performance click here: https://am.gs.com/en-us/advisors/funds/detail/PV105259/38149W630/goldman-sachs-nasdaq-100-premium-income-etf.

Sign In or Subscribe to Advisor Upside to read this article
Market insights, practice essentials, and industry updates.