Good morning.
Some 70 million American children now have Trump Accounts … sort of.
The accounts, which are seeded with $1,000 to invest in low-cost index mutual funds and ETFs and remain locked until age 18, officially launched this summer. Since then, more than 8 million children have been signed up.
But just last week, President Donald Trump announced that “every single eligible minor child in America” now has an account. Plus, eligible wealthy investors can donate stocks to accounts. There’s a catch, though.
While technically every child has been automatically enrolled, parents still need to formally claim and activate their accounts. In fact, plenty of parents may not even realize their kids are able to start their investing journeys.
What are ya waiting for, mom and dad?
It’s Complicated: Issues with Private Assets Aren’t Deterring Advisors
Wall Street is betting big on alternative investments, particularly private markets. Major asset managers have launched products to bring private investments to more clients, and Washington has pushed to make alternatives a more common feature of 401(k) plans.
However, while more advisors are offering privates, their confidence in explaining them to clients has declined, raising questions about whether the push for broader adoption is outpacing advisors’ preparedness. Just 61% of advisors said they felt somewhat or extremely comfortable explaining the private investments they offer, down from 68% in 2025, according to Morningstar research. Meanwhile, 40% said they offer private-market investments, up from 35% last year.
Choose Wisely
Access is no longer the only barrier to private markets. The bigger challenge is finding exceptional managers, said Will Sterling, CIO of TritonPoint Wealth. “You can’t democratize alpha,” he told Advisor Upside.
Asset managers are trying to make alternative investments more attractive to advisors by simplifying them and packaging them in familiar strategies. Just last week, Morgan Stanley rolled out nine model portfolios that mostly hold public assets but also include 8% to 12% allocations to private equity, private credit, real estate and infrastructure. This month, Morningstar expects to launch its own suite of alts model portfolios, featuring strategies from Apollo, Franklin Templeton and JPMorgan.
However, returns can vary widely across managers, making selection especially critical, Sterling said. “A lot of charts used in presentation decks show the top quartile versus bottom quartile and the dispersion that exists in private markets relative to public markets,” he said. “Making sure you’re getting in at least the top 50%, if not that top quartile, is of the utmost importance.”
Advisors’ due-diligence concerns are also growing, per Morningstar:
- Some 46% cited concerns about fees and fee transparency, up from 36% last year.
- More than 40% flagged limited liquidity, compared with 36% in 2025.
- Meanwhile, 35% expressed concern about a lack of transparency into underlying holdings, up from 32%.
Carve It Up. There’s no standard allocation for alternatives comparable to the traditional 60/40 portfolio of stocks and bonds. The right amount depends on the client, said Josh Glenn, founder of Focused Wealth Management, who recommends allocating between 5% and 20% of some clients’ portfolios to alts.
Glenn began exploring the investments during the pandemic and has since grown comfortable with them. “It was clear that markets were changing, and we didn’t want to miss out,” he told Advisor Upside. “In 2022, when equities and bonds were beaten up, alts were the bright spot in many client portfolios.”
Others remain skeptical, feeling that while alts can potentially benefit some clients, those instances tend to be rare. “Most investors will benefit from increased simplicity, not increased complexity in their financial plans,” said James Eppes, founder of Eppes Wealth Management.
Clients on GLP-1s Are Making Weighty Financial Decisions
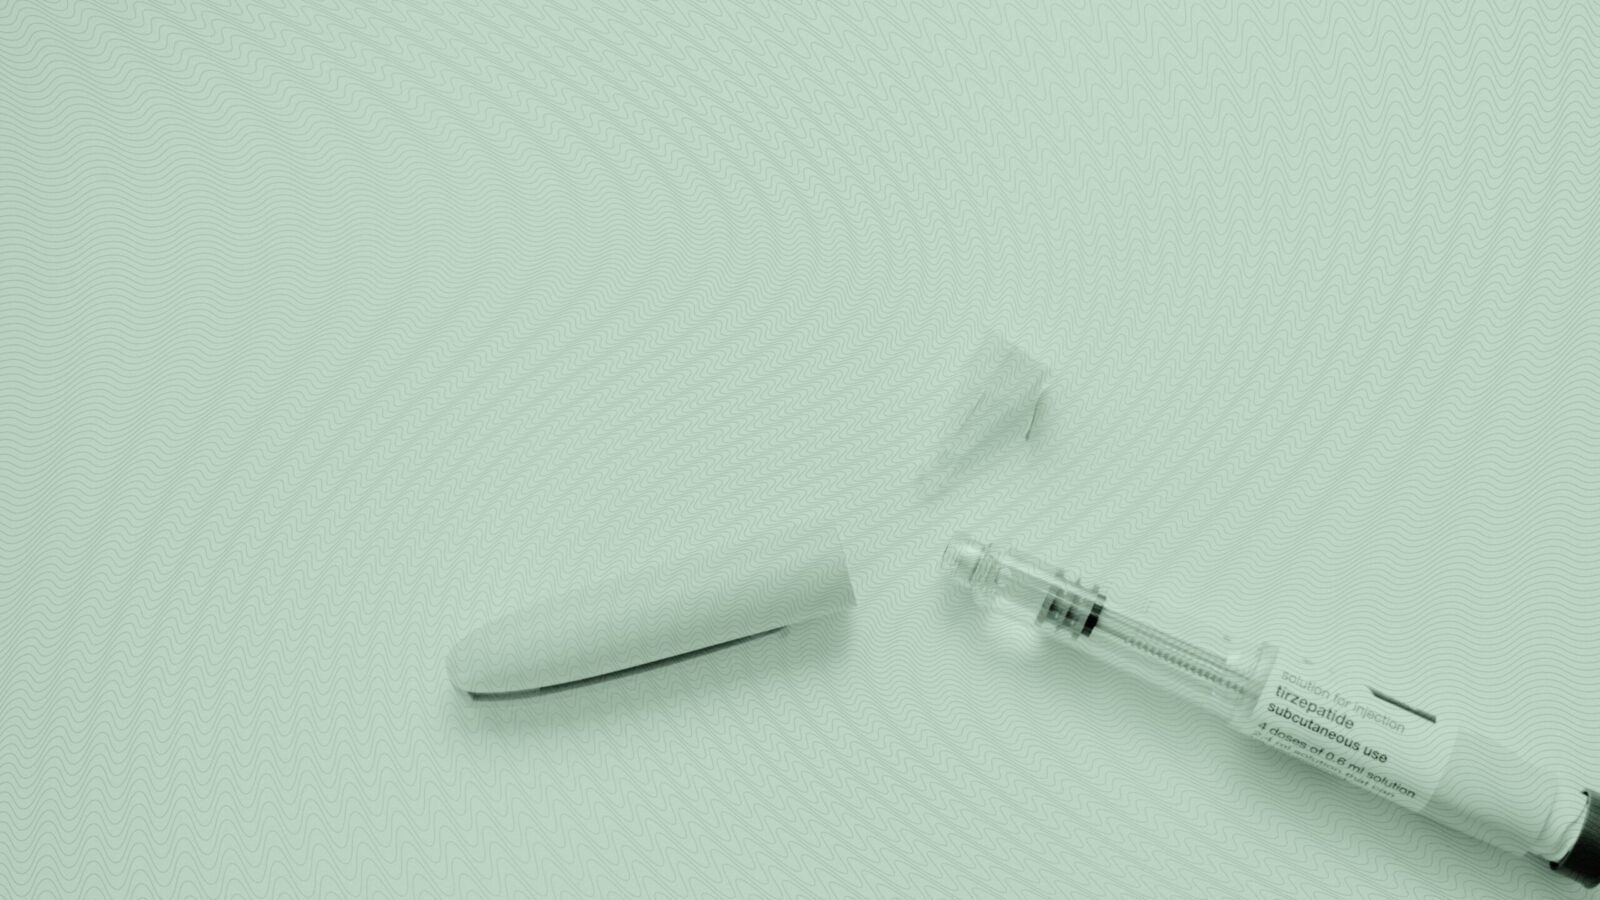
Here’s the skinny.
More than half of those using weight-loss medications like GLP-1s say they fear having to choose between paying for the drugs and saving for retirement, according to a recent survey from the Nationwide Retirement Institute. That includes 14% who have already started contributing less to their retirement goals and 14% who have taken money out of accounts to afford medications. The numbers are a reminder for advisors to have ongoing conversations with clients about their health, since healthcare costs are some of the hardest expenses to predict in retirement.
“The question I teach advisors to ask to open up the conversation is: ‘Tell me what you do to take care of your health,’” said Dr. Carolyn McClanahan, a physician and CFP at Life Planning Partners. It’s a nonjudgmental question and allows advisors to gauge where their clients are at. “I want to plan for who you are, not who you want to be.”
Health Is Wealth
The health benefits of weight loss mean that clients on weight-loss drugs may live longer than they otherwise would. That means planning for a longer retirement, but it’s not a zero-sum game. “If people are better able to have better health outcomes in retirement, that means maybe it’s a little bit of an expense now, but we’re also avoiding more serious issues down the road,” said Marguerita Cheng, CEO at Blue Ocean Global Wealth. “I cannot take credit for this mantra, but I live by it: ‘Too many people spend their health to gain wealth, only have to spend their wealth to regain their health.’”
Data from the Nationwide report show changes in how people view retirement and long-term care, for better or worse:
- The survey noted 59% said the health benefits of GLP-1s make them feel less pressured to save for retirement, while 57% said they’re less concerned about needing additional health or long-term care insurance.
- Still, another 59% said they worried about being able to afford GLP-1s in retirement — and the same amount also said they expected advisors to guide them on the financial implications of being on the drugs.
Healthy Skepticism. Still, with the realities of America’s healthcare system, clients can’t just write off the possibility of increased healthcare costs in the future, especially as more employers move to end coverage of weight-loss drugs. “Our healthcare system is very broken, and we don’t know what it’s going to look like in the future,” McClanahan said. “Even though you’re living healthier, it doesn’t mean your healthcare expenses are going to go down. It just means you’re going to have them longer because ideally you’re going to live longer.”