Big Banks Earning Week Puts Fears of Slowing Capital Markets Activity in Focus
The major US banks will report third quarter results this week, kicking off an earnings season that will be measured against investor worries.
Sign up for smart news, insights, and analysis on the biggest financial stories of the day.
It’s time to take the pulse of Wall Street. JPMorgan, Goldman Sachs, Citigroup and Wells Fargo are set to report results tomorrow, as America’s big banks kick off the first wave of the third quarter earnings season. Morgan Stanley and Bank of America are scheduled to follow on Wednesday.
They have a challenge ahead of them: meeting an awfully high bar set by worried investors who have dumped shares in recent weeks even though the economy and credit quality remain on sound footing.
Theory vs. Practice
Lately, investors are Dostoevsky-level pessimistic about lenders in today’s high yield environment. The bank sector is among the worst-performing on markets, with the iShares S&P U.S. Banks UCITS ETF down 7.7% in the last month. Compare that to the S&P 500 and Nasdaq Composite, where the mood has been more like an upbeat Mitch Albom paperback: Both hit all-time highs last week, driven by tech (and not much else).
Higher interest rate environments are generally seen as good for banks, but that’s not always the case. “In theory, higher rates = higher loan interest = greater bank profit,” explained analysts at broker CMC Markets. “In practice, if rates rise too quickly and remain high for too long, customers stop taking out mortgages and investment loans, and existing borrowers struggle to repay. A bank that fails to benefit from a higher margin starts losing volume and must set aside provisions for bad debts.” Those fears have been compounded by the risk of inflation and rising energy prices, which already have US consumers expressing record levels of frustration. While household spending has been incredibly resilient, any slowdown would impact banks’ balance sheets by hurting their fee incomes.
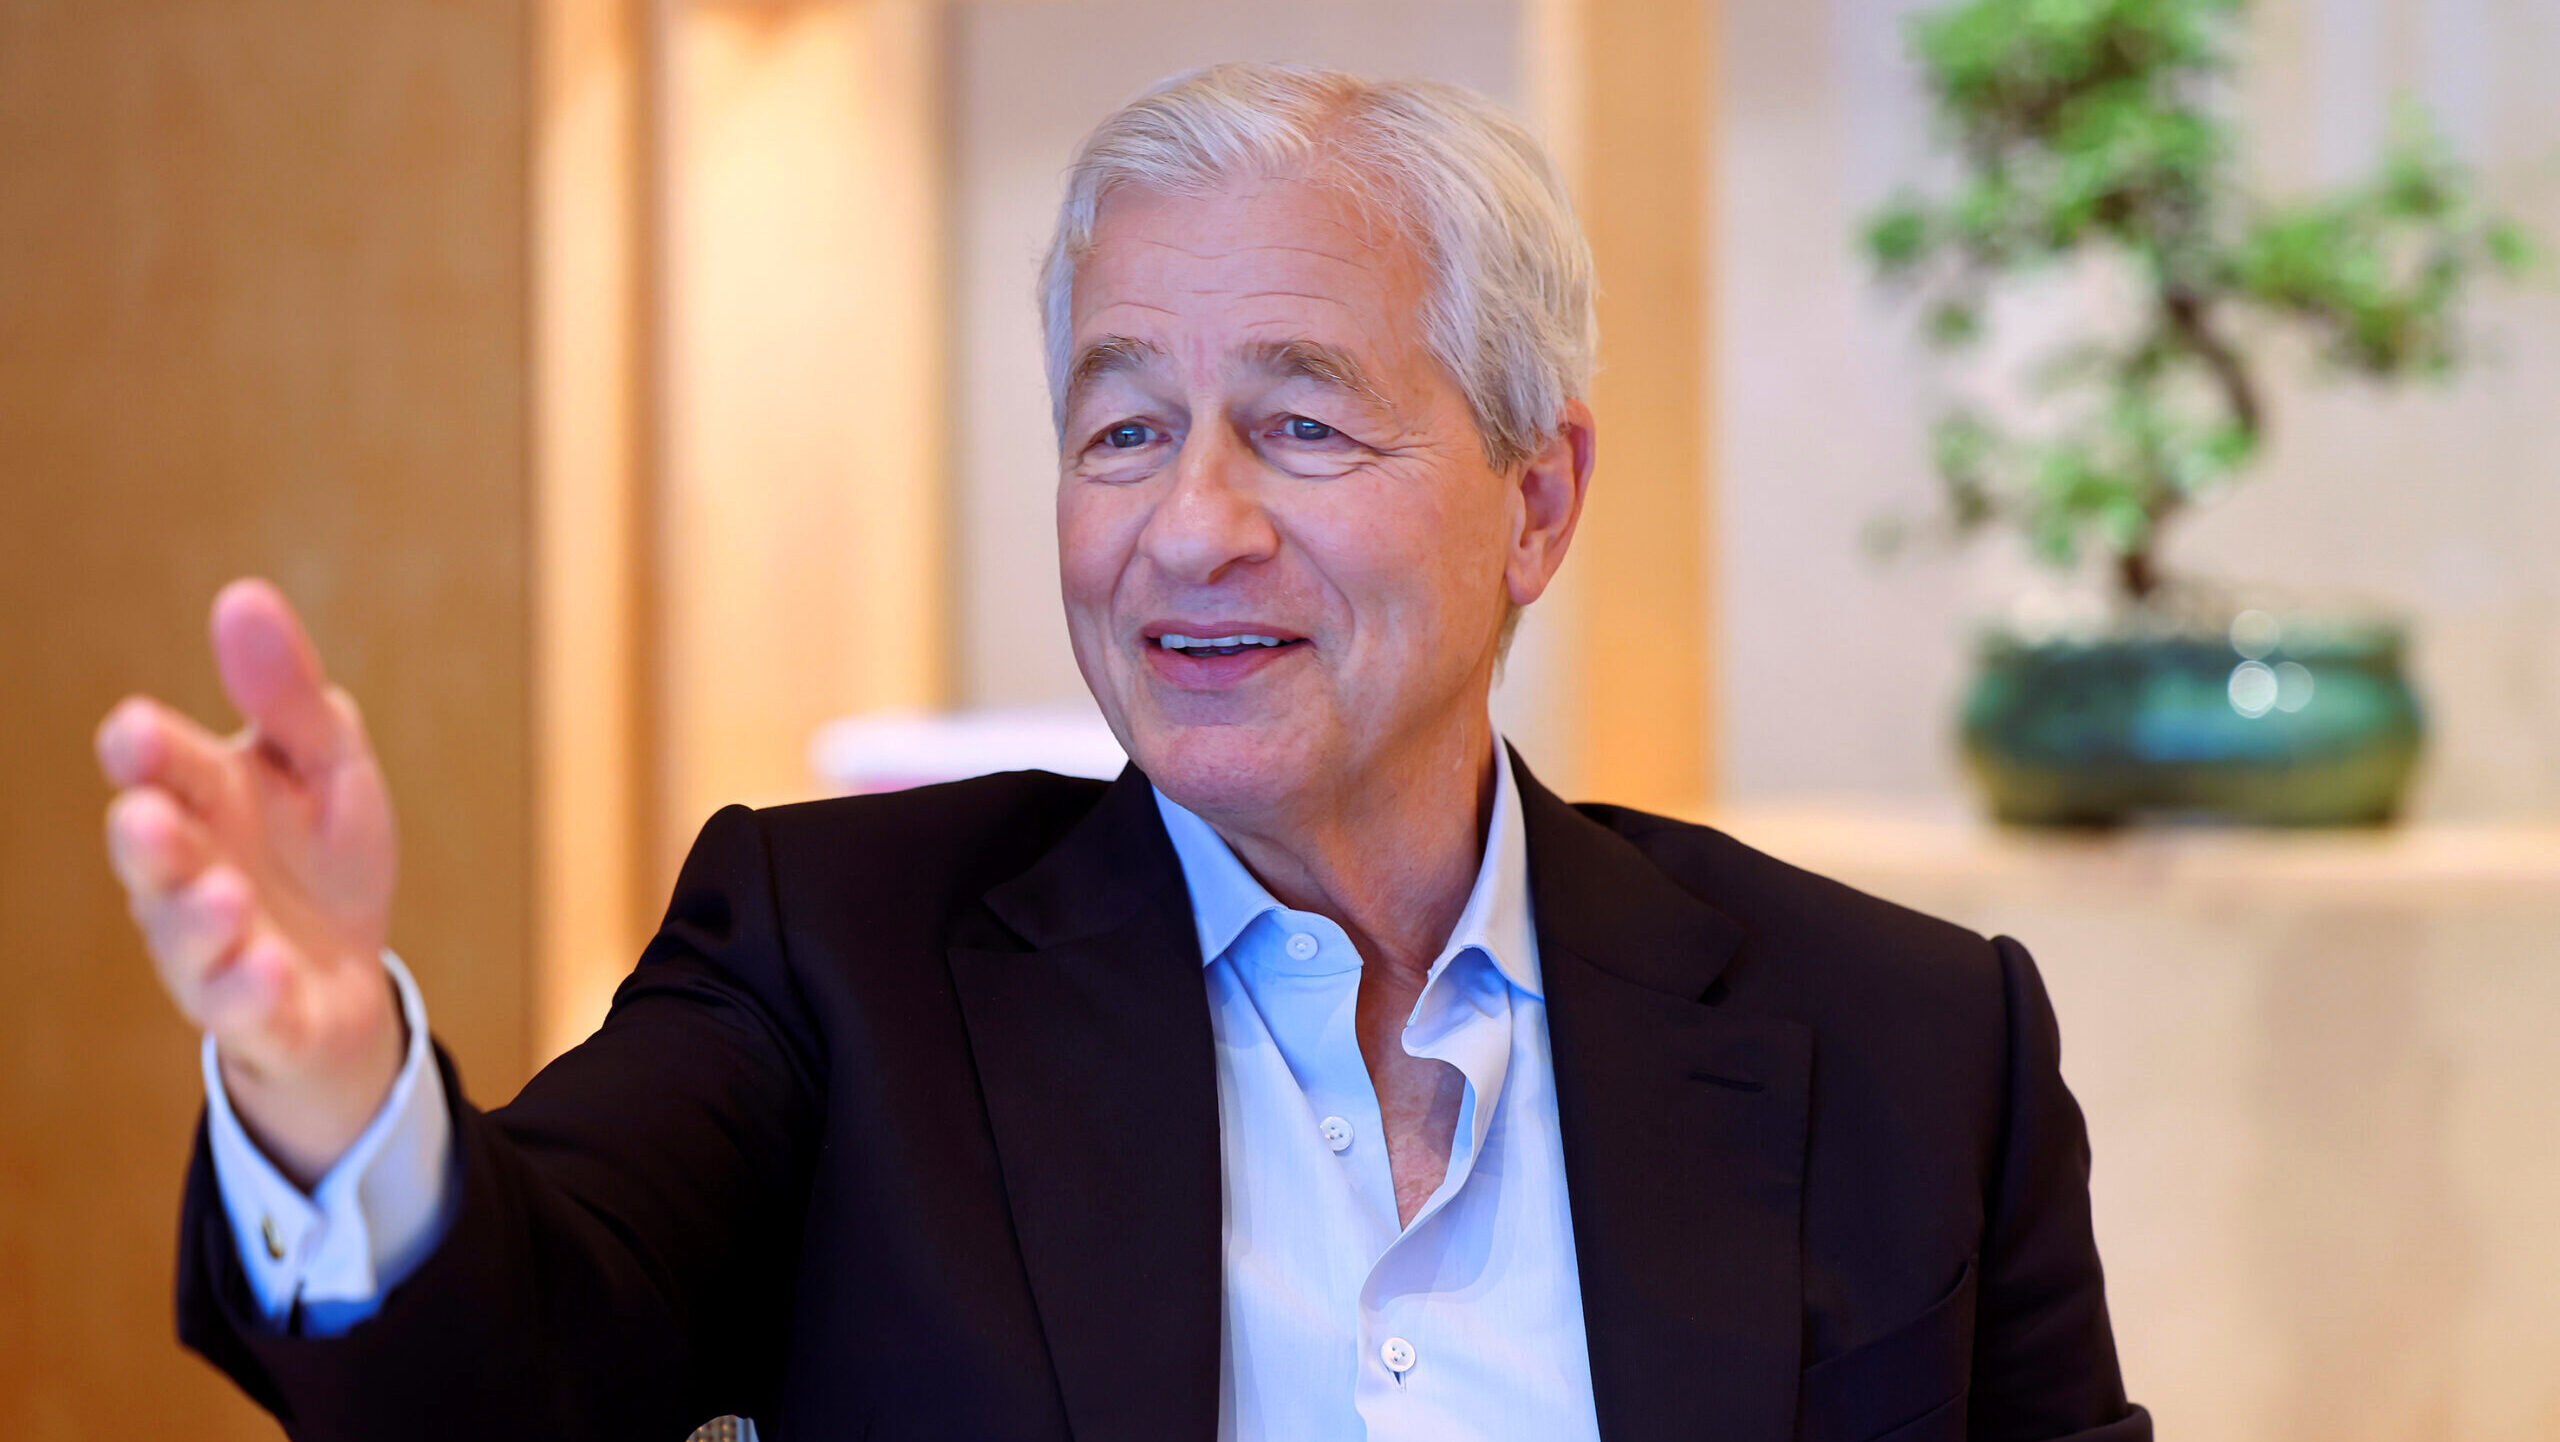
It’s not just consumers in the crosshairs. JPMorgan CEO Jamie Dimon has spent months warning that companies may be unprepared for the one-two punch of higher prices and higher borrowing costs. “I think there’s a risk that inflation is sticky, that rates continue to go up and so, for corporations, whether you’re leveraged or not, when you have to [refinance] or borrow money are you prepared for higher credit spreads?” he stressed in a podcast interview last week. With that in mind, this week’s earnings will put capital markets activity in the spotlight:
- Heading into earnings season, Oppenheimer analysts said they expect “plain vanilla” banking activity — loans, credit and costs — to come in just fine. But they warned of capital markets income at the low end of the market’s expectations and, expecting a dealmaking slowdown, slashed their aggregate investment banking revenue estimate by 9.5%.
- Raymond James analysts expect sound fundamentals, too, and are more optimistic about quarterly earnings beats (Oppenheimer expects only JPMorgan to top the Street’s expectations). But they emphasized that executives will have to demonstrate “credible and achievable” 2027 targets that account for higher interest rates and their impacts to quell investor anxiety.
Where There’s Smoke: Evidence in support of Dimon’s warning has already materialized in credit markets. JPMorgan reported earlier this month that the value of deeply distressed US loans rose to $65 billion in the third quarter, up from $40 billion a year ago and the highest in more than six years.