High-Volume Semi Production, Souped-Up Roadster Offer Jolt for Tesla Investors
Last month, Tesla’s vehicle sales fell 12.4% in China. US sales have been even worse, dropping 14.6% in the first half of 2026.
Sign up for smart news, insights, and analysis on the biggest financial stories of the day.
The car is back in the driver’s seat at Tesla. After over six years of delays, the Elon Musk-led automaker is set to reveal its second-generation Roadster on Thursday at SpaceX’s McGregor, Texas, test site.
Tesla shares could use the jolt. They entered this week down 17% in 2026 and vehicle sales are slipping in the world’s two largest car markets. But analysts at Morningstar, who rate the stock undervalued, say vehicles at Tesla could find themselves in the fast lane starting next year.
On the Roadster Again
Last month, Tesla’s vehicle sales fell 12.4% in China. US sales have been even worse, dropping 14.6% in the first half of 2026. Still, the company has not lost its core loyalists, with superfans and car enthusiasts who haven’t even seen the final version of the new Roadster yet depositing $50,000 just to get in the queue to buy one. Patent filings show the new Roadster’s aerodynamic design could include a Porsche 911-like wing and rumored features include sub-two-second zero-to-60 mph acceleration, over 250 mph top speed, and a 620-mile battery life. Musk said last year that production would be capped at 10,000 units per year, though there may also be a limited edition version with James Bond-like cold-gas thrusters co-developed by SpaceX for anyone who wants to get side-eye on the freeway.
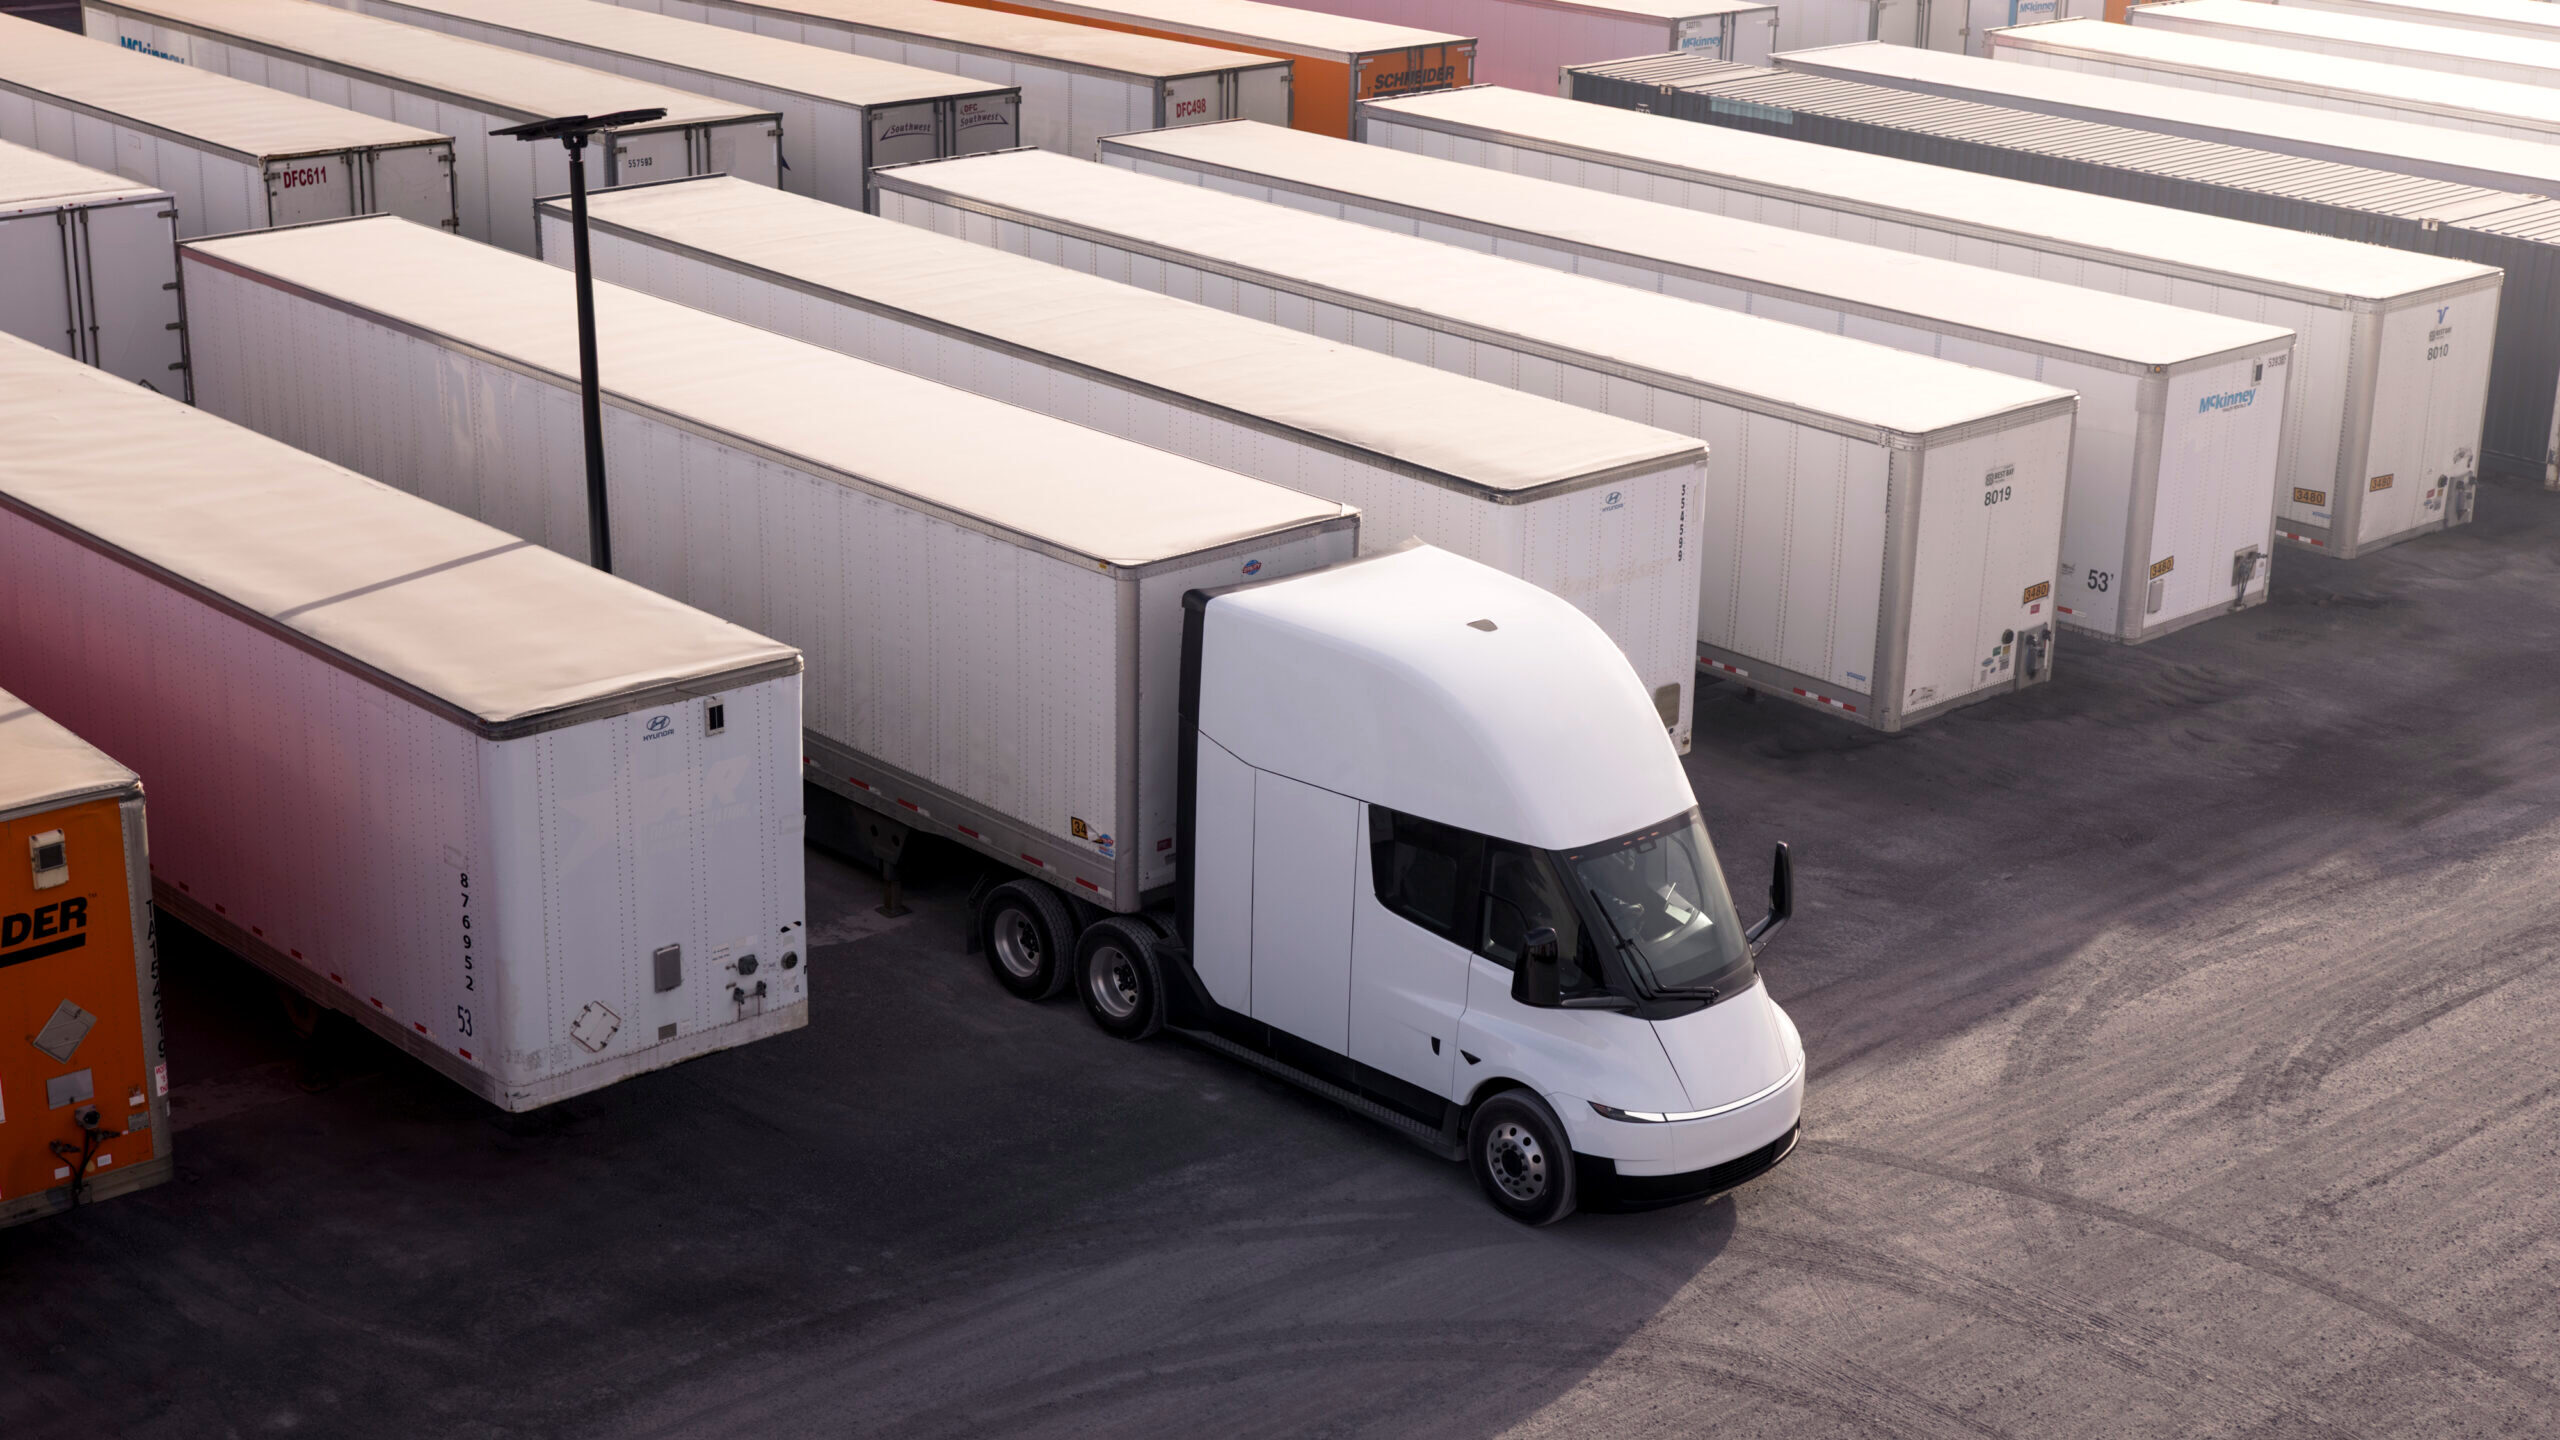
Making good on the long-delayed Roadster isn’t the only way in which Tesla’s auto division is gearing up. Last week, the company launched high-volume production of its electric semi-trailer truck, the Tesla Semi. A dedicated factory in Nevada will produce up to 50,000 units per year, putting the Semi on the road after it also suffered years of delays, with production originally slated for 2019. But the days when new vehicle rollouts were Tesla’s most promising venture may already be a thing of the past, with Morningstar’s view bolstered by the company’s plans for AI, clean energy and humanoid robots, not a 007 Roadster:
- Morningstar estimates Tesla’s energy revenue will grow 30% annually from 2027 to 2031 compared with 17% for automotive revenue.
- They also project 30% annual growth at the “Services and Other” segment, a onetime money-loser that includes vehicle repairs, used car sales, Tesla’s charging network, insurance and software. It grew revenue 19% last year to $12.5 billion.
Hail Fail: According to Zacks Investment Research, the average Wall Street price target on Tesla, at $406.30, is not quite as bullish as Morningstar, but still implies a 9.2% upside. In fact, the people on Wall Street who might end up the most worried are the cab drivers: Morningstar estimates Tesla’s autonomous Cybercab will ultimately be 25% cheaper than human-driven rides for hire.
Recent News
-
The Gig’s Up: Robotaxis, Delivery Drones Reshape the Side-Hustle Market

Photo illustration by Connor Lin / The Daily Upside, Photo by Chanakon Laorob via iStock
-
Musk’s Boring Company Scores $23 Billion Valuation Despite Slow Progress

Photo via The Boring Company/X

-
Uber, Waymo and Tesla Speed Toward Driverless Future

Photo via Uber/Avride