Some Workers Still Want to Cut and Run at 62
Phased retirement is appealing within some industries, but many blue-collar workers with physically demanding jobs want to quit earlier.
Sign up for smart news and actionable insights on the strategies, products, and policy shifts shaping retirement outcomes.
We all know what can happen when we make assumptions. Still, we feel pretty confident that readers of this newsletter have heard about phased retirements.
Some people who enjoy their work and worry about abruptly transitioning away from the nine-to-five structure choose to reduce their hours, change into a less demanding role or explore fulfilling encore careers. It’s a growing reality in a variety of industries, per Marsh’s latest Global Talent Trends report, which found just 16% of workers intend to stop all at once.
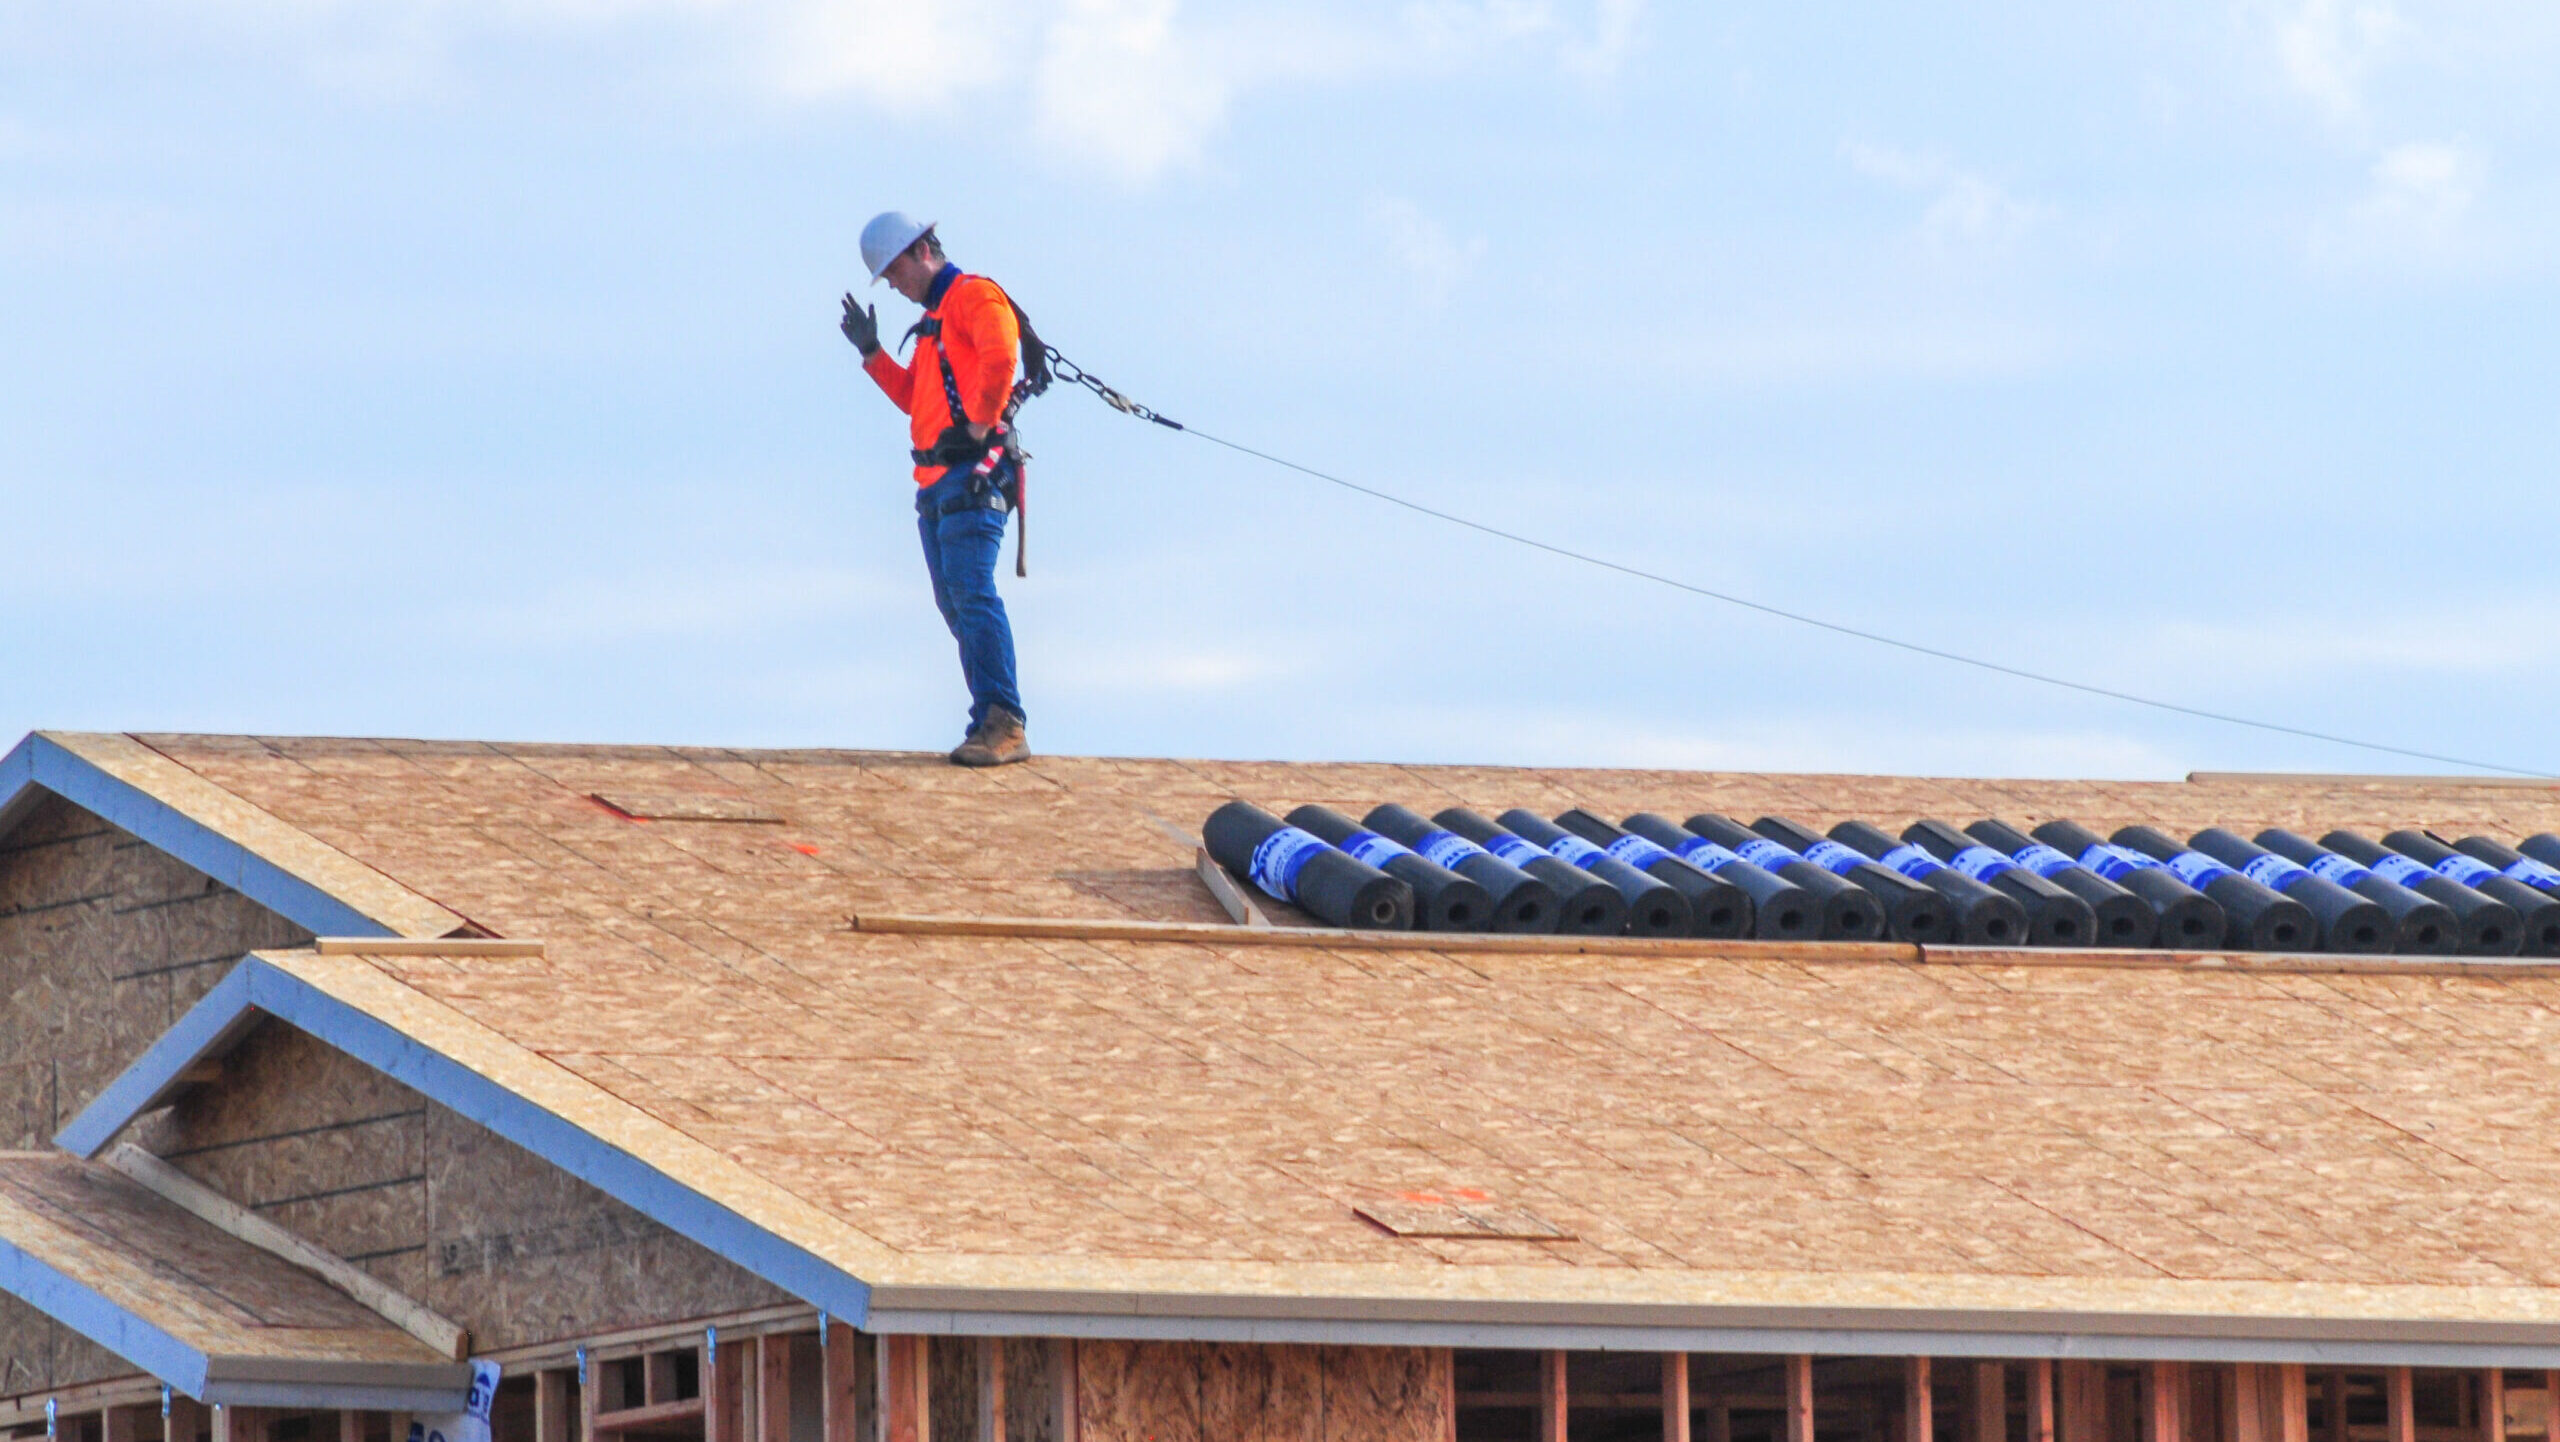
Those numbers are striking, but phased retirements are by no means the norm, said Joel Bird, a private wealth advisor and CEO at Legacy Financial Partners in Bismarck, North Dakota. Bird’s practice focuses on rural clients whose work is broadly blue collar. For this group, phased retirements can sound more like a failure to prepare for one’s golden years than something to be desired.
“A lot of our clients are in agriculture, coal and wind power,” Bird said. “They still have more of a traditional idea of retirement being a single event, which factors into our planning process.”
Calling It Quits
Survey data from the Employee Benefit Research Institute show nearly half (46%) of retirees left the workforce earlier than planned:
- “Many who say they retired earlier than planned did so because of a hardship, such as a health problem or disability (41%).”
- “Thirty-five percent say that they retired due to changes at their company, but a similar share say they could afford to retire earlier (36%).”
It’s particularly rewarding to see a client who has put in so much physical labor on the job reach a point where they can step away on their own terms, Bird said. But as with other types of workers, it can be hard for blue-collar clients to feel truly ready for retirement. As a result, underspending can be as common as overspending.
“Monte Carlo simulations and stress-testing are important tools,” Bird said. “Another challenge is sparking intergenerational discussion about wealth and inheritance. A lot of clients who’ve built up real wealth worry about creating a sense of entitlement in their kids.”
Be Honest. “The traditional view of retirement isn’t old fashioned,” Tax Alpha Companies founder Matt Chancey said. “It’s honest.”
An office worker may be able to ease into retirement over five years, but a nurse on 12-hour nights usually can’t. “The body picks the date,” Chancey said. “Good planning respects that instead of arguing with it. Shift workers also tend to think about money in paychecks, not account balances. That instinct is closer to right than most of what Wall Street sells. Retirement is an income, not a number.”