Bond Yields at 2007 Levels Undermine 60/40 Portfolio Rationale
The rout has been caused by energy shocks, surging US government debt, inflation and capital investment the size of national GDPs.
Sign up for smart news, insights, and analysis on the biggest financial stories of the day.
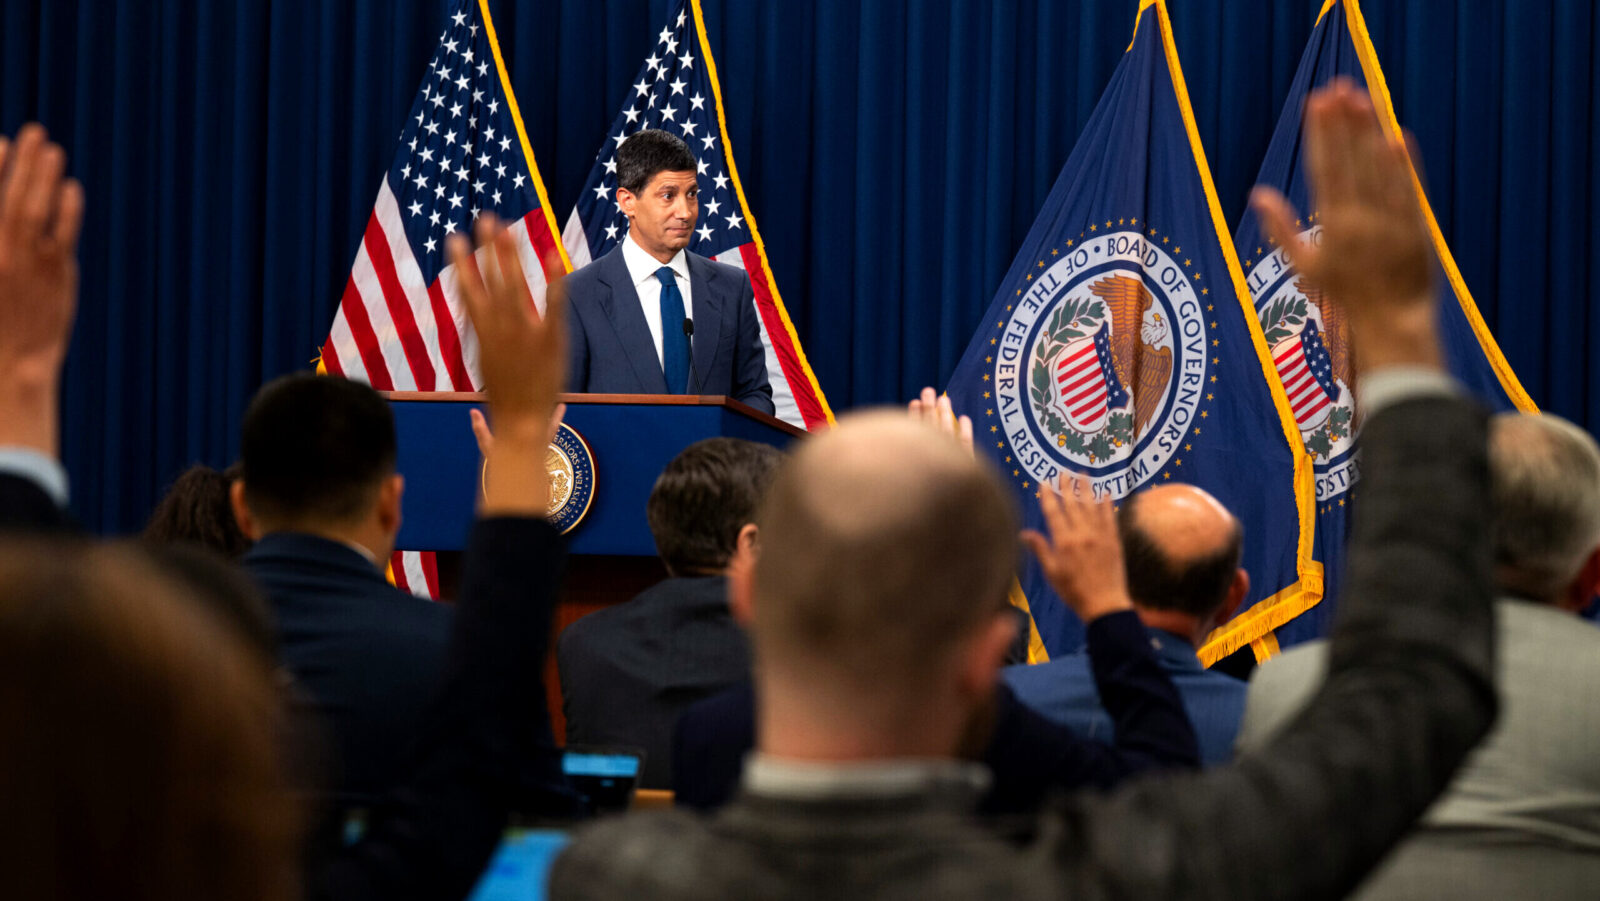
The last time the 10-year US Treasury yield was this high, Apple was promoting its first-ever iPhone and Rihanna’s Umbrella was topping Billboard’s Hot 100.
The yield, which serves as a proxy for long-term rates, topped 5% on Tuesday, its highest level since 2007. It’s just the latest move in a global bond market rout caused by myriad factors including energy shocks, surging US government debt, inflation and capital investment the size of national GDPs, much of it for AI projects. The odds that the Federal Reserve will hike interest rates today have surged above 90%, which is also pushing up yields.
PIP for Bonds
If bonds were getting reviewed for their job performance in the traditional stock-bond portfolio, it would be time for an improvement plan. The asset is known (and appreciated) for zigging when stocks zag. As a result, experts have been debating whether it’s time to pull out the coffin for the 60/40 portfolio since 2022, when increased inflation started causing bonds to exacerbate stock losses rather than counteract them.
The popular portfolio strategy of investing 60% of portfolios in stocks and 40% in bonds is famous for offering investors the best of both worlds: steady income from bonds and growth potential from stocks. However, when the 10-year Treasury climbs above 5.25% for an extended period of time, the stock-bond correlation almost always turns positive. Now, we may be nearing that inflection point:
- “The 60/40 portfolio is broken because equity returns are driven by AI concentration rather than the business cycle, while bond returns are now driven by fiscal constraints rather than cycle dynamics,” Torsten Slok, chief economist at Apollo, recently wrote. If the AI trade reverses or markets become more worried about government deficits, stocks and bonds could both suffer, he added.
- Matt Rowe, senior portfolio manager at Man Group, told the Financial Times that the bond component of portfolios needs to be reconsidered when it comes to risk diversification, potentially by looking at the difference between “crisis correlation” and “non-crisis correlation” between asset classes.
Pummeled Risk Premium: In a recent note, JPMorgan said that the equity risk premium (the extra return investors expect to get for holding stocks instead of bonds) of the S&P 500 has fallen to its lowest level since 2002. Stocks, the analysts wrote, could become more sensitive to ups and downs of bond yields and we could see the reinforcement of the positive bond-equity correlation.
Recent News
-

Photo illustration by Connor Lin / The Daily Upside
-
Photo illustration by Connor Lin / The Daily Upside