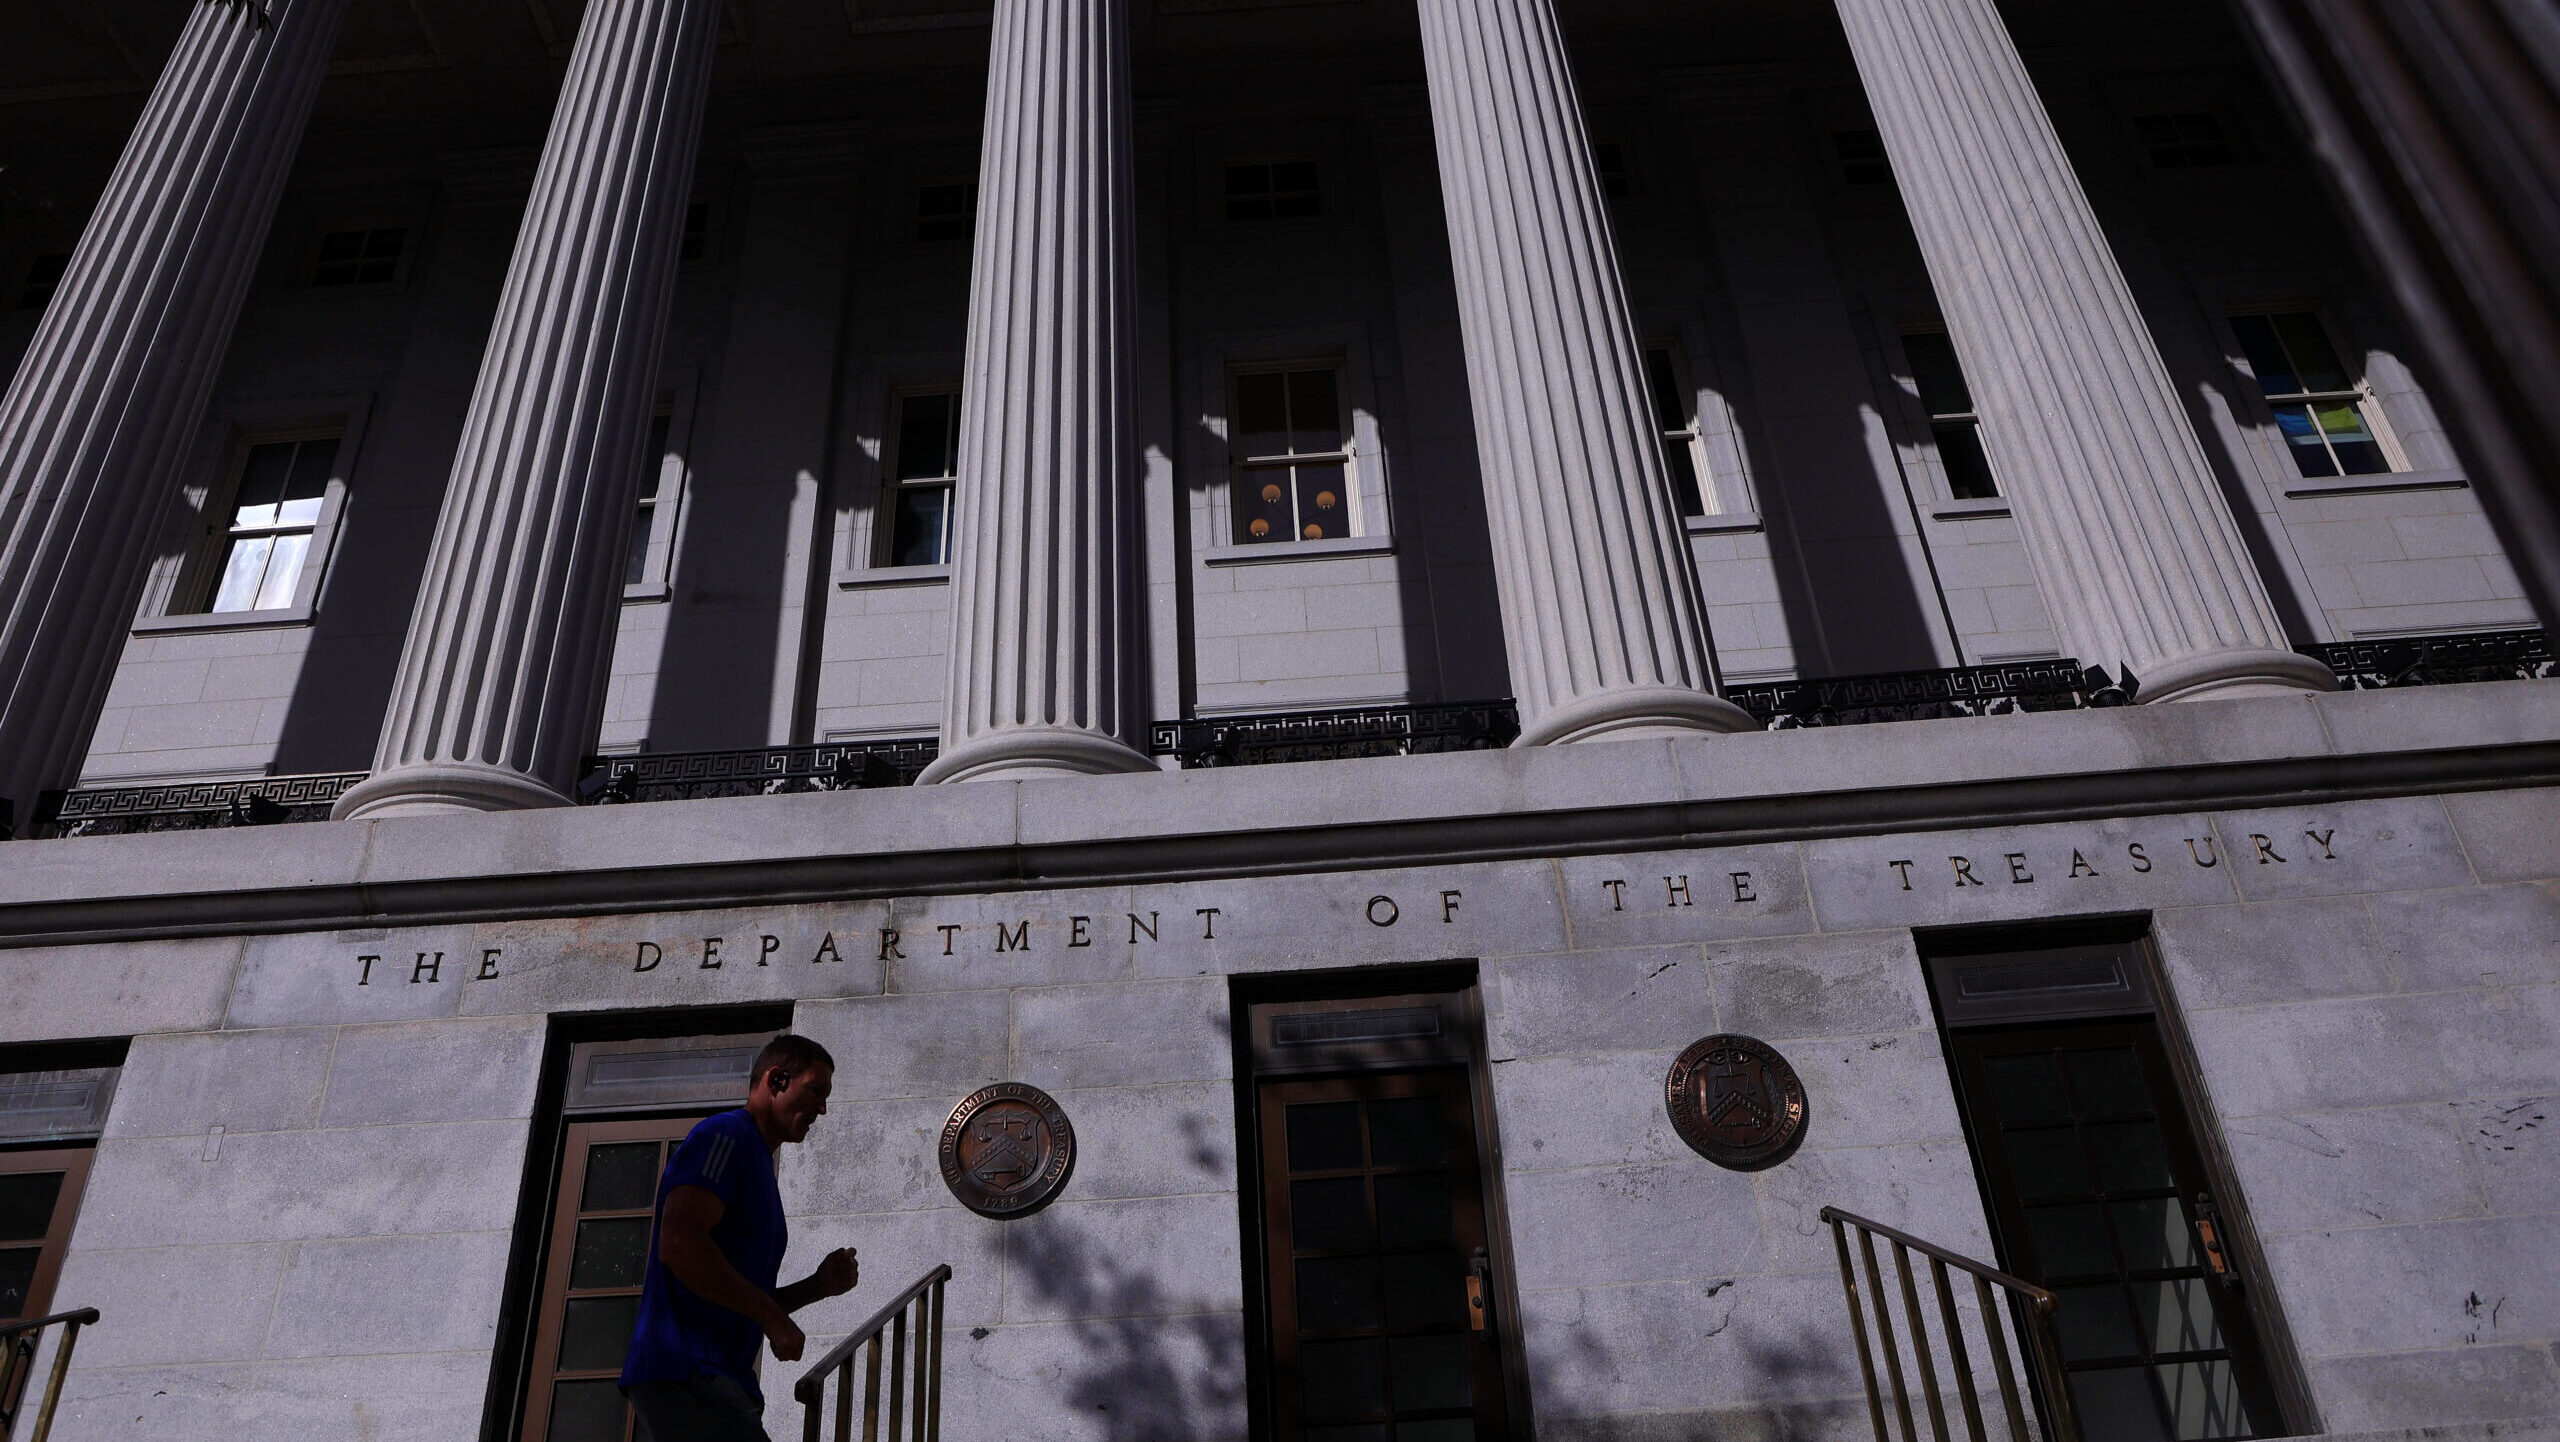
Brisk $39 Billion Treasury Auction Offers Bond Market Breather
The yield on the yield fell to 5.282%, after rising to the highest level since 2002 ahead of Wednesday’s auction.
Sign up for smart news, insights, and analysis on the biggest financial stories of the day.
Things went from spooked to sanguine in a matter of hours on bond markets Wednesday. At first, the yield on the benchmark 10-year US Treasury note spiked to 5.36%, the highest level since 2002.
But then $39 billion in 10-year notes sold at a brisk afternoon Treasury auction, and the surge in demand helped bring the yield down to 5.282%, offering a breather from the bond bloodbath.
Back by Popular Demand
Bonds have endured weeks of selloffs, with investors chewing their fingernails over the risks of inflation, war, energy prices, public spending, government debt, rate hikes and (because it’s October) creepy ghouls like the ghost of the 2003 Treasury selloff. Yields have come under even more pressure with AI infrastructure spending and corporate debt competing for capital. “Investors consequently demanded higher returns to commit capital, creating headwinds for long-duration bonds and interest rate-sensitive areas of the market,” said Fifth Third Wealth Advisors Chief Investment Officer Chris Osmond, in a Wednesday report on the market’s third quarter.
Yesterday’s auction eased some fears, especially as it pertains to demand. The 5.3% auction yield was the highest since 2000, but it also got the job done. Investors rushed to lock in long-term gains with Uncle Sam: James Thorne, the chief market strategist at Wellington-Altus Private Wealth, pointed out that primary dealers, the big banks responsible for buying whatever bonds the market doesn’t snap up, took a mere 2.5% of Wednesday’s haul, the lowest share on record. “That undercuts claims of a buyer shortage,” he wrote. “Buyers bid aggressively at current yields, hardly the behavior one would expect from a market anticipating a dramatic further rise in long-term rates.” A reprieve from the bond sell-off would crucially offer a boon to stocks, which analysts have warned are at risk of long-term yields above 5% prompting investors to rotate into fixed income. In fact, Saxo Bank Chief Investment Strategist Charu Chanana, wrote this week that most S&P 500 sectors are already taking a pummeling for this reason, but that the index is “hiding the damage”:
- “Over the past month, the S&P 500 is up around 0.7%,” she noted. “Yet only two sectors are positive: technology, up 7.1%, and communication services, up 3.3%. Every other sector is down. Financials have fallen around 7%, materials 6.6%, utilities 6.2% and real estate 6.1%.”
- “That tells us something important: Higher bond yields are already hurting equities,” she wrote. “The pain is simply being masked by the strength of AI and megacap technology.”
Help at Home: Notes released from the Federal Reserve’s September policy meeting on Wednesday show officials expect to raise interest rates before the end of the year, but they signaled no immediate need for action. Markets are pricing the odds of an October rate hike, which would put more upward pressure on bond yields, at just 17%. Consumer borrowers, especially homebuyers, stand to benefit from any relief. The Mortgage Bankers Association said Wednesday that mortgage applications fell 4.2% last week as the 30-year fixed mortgage rate hit a three-year high of 7.49%. “Very few homeowners have an incentive to refinance at these rates, and the jump in borrowing costs has caused many potential borrowers to step back from the purchase market,” said MBA’s Deputy Chief Economist Joel Kan.