Ahead of GM Earnings, Disciplined Pricing and New Business Lines Come into Focus
CEO Mary Barra reiterated last week that GM is on schedule to release “eyes-off, hands-off” self-driving technology by 2028.
Sign up for smart news, insights, and analysis on the biggest financial stories of the day.
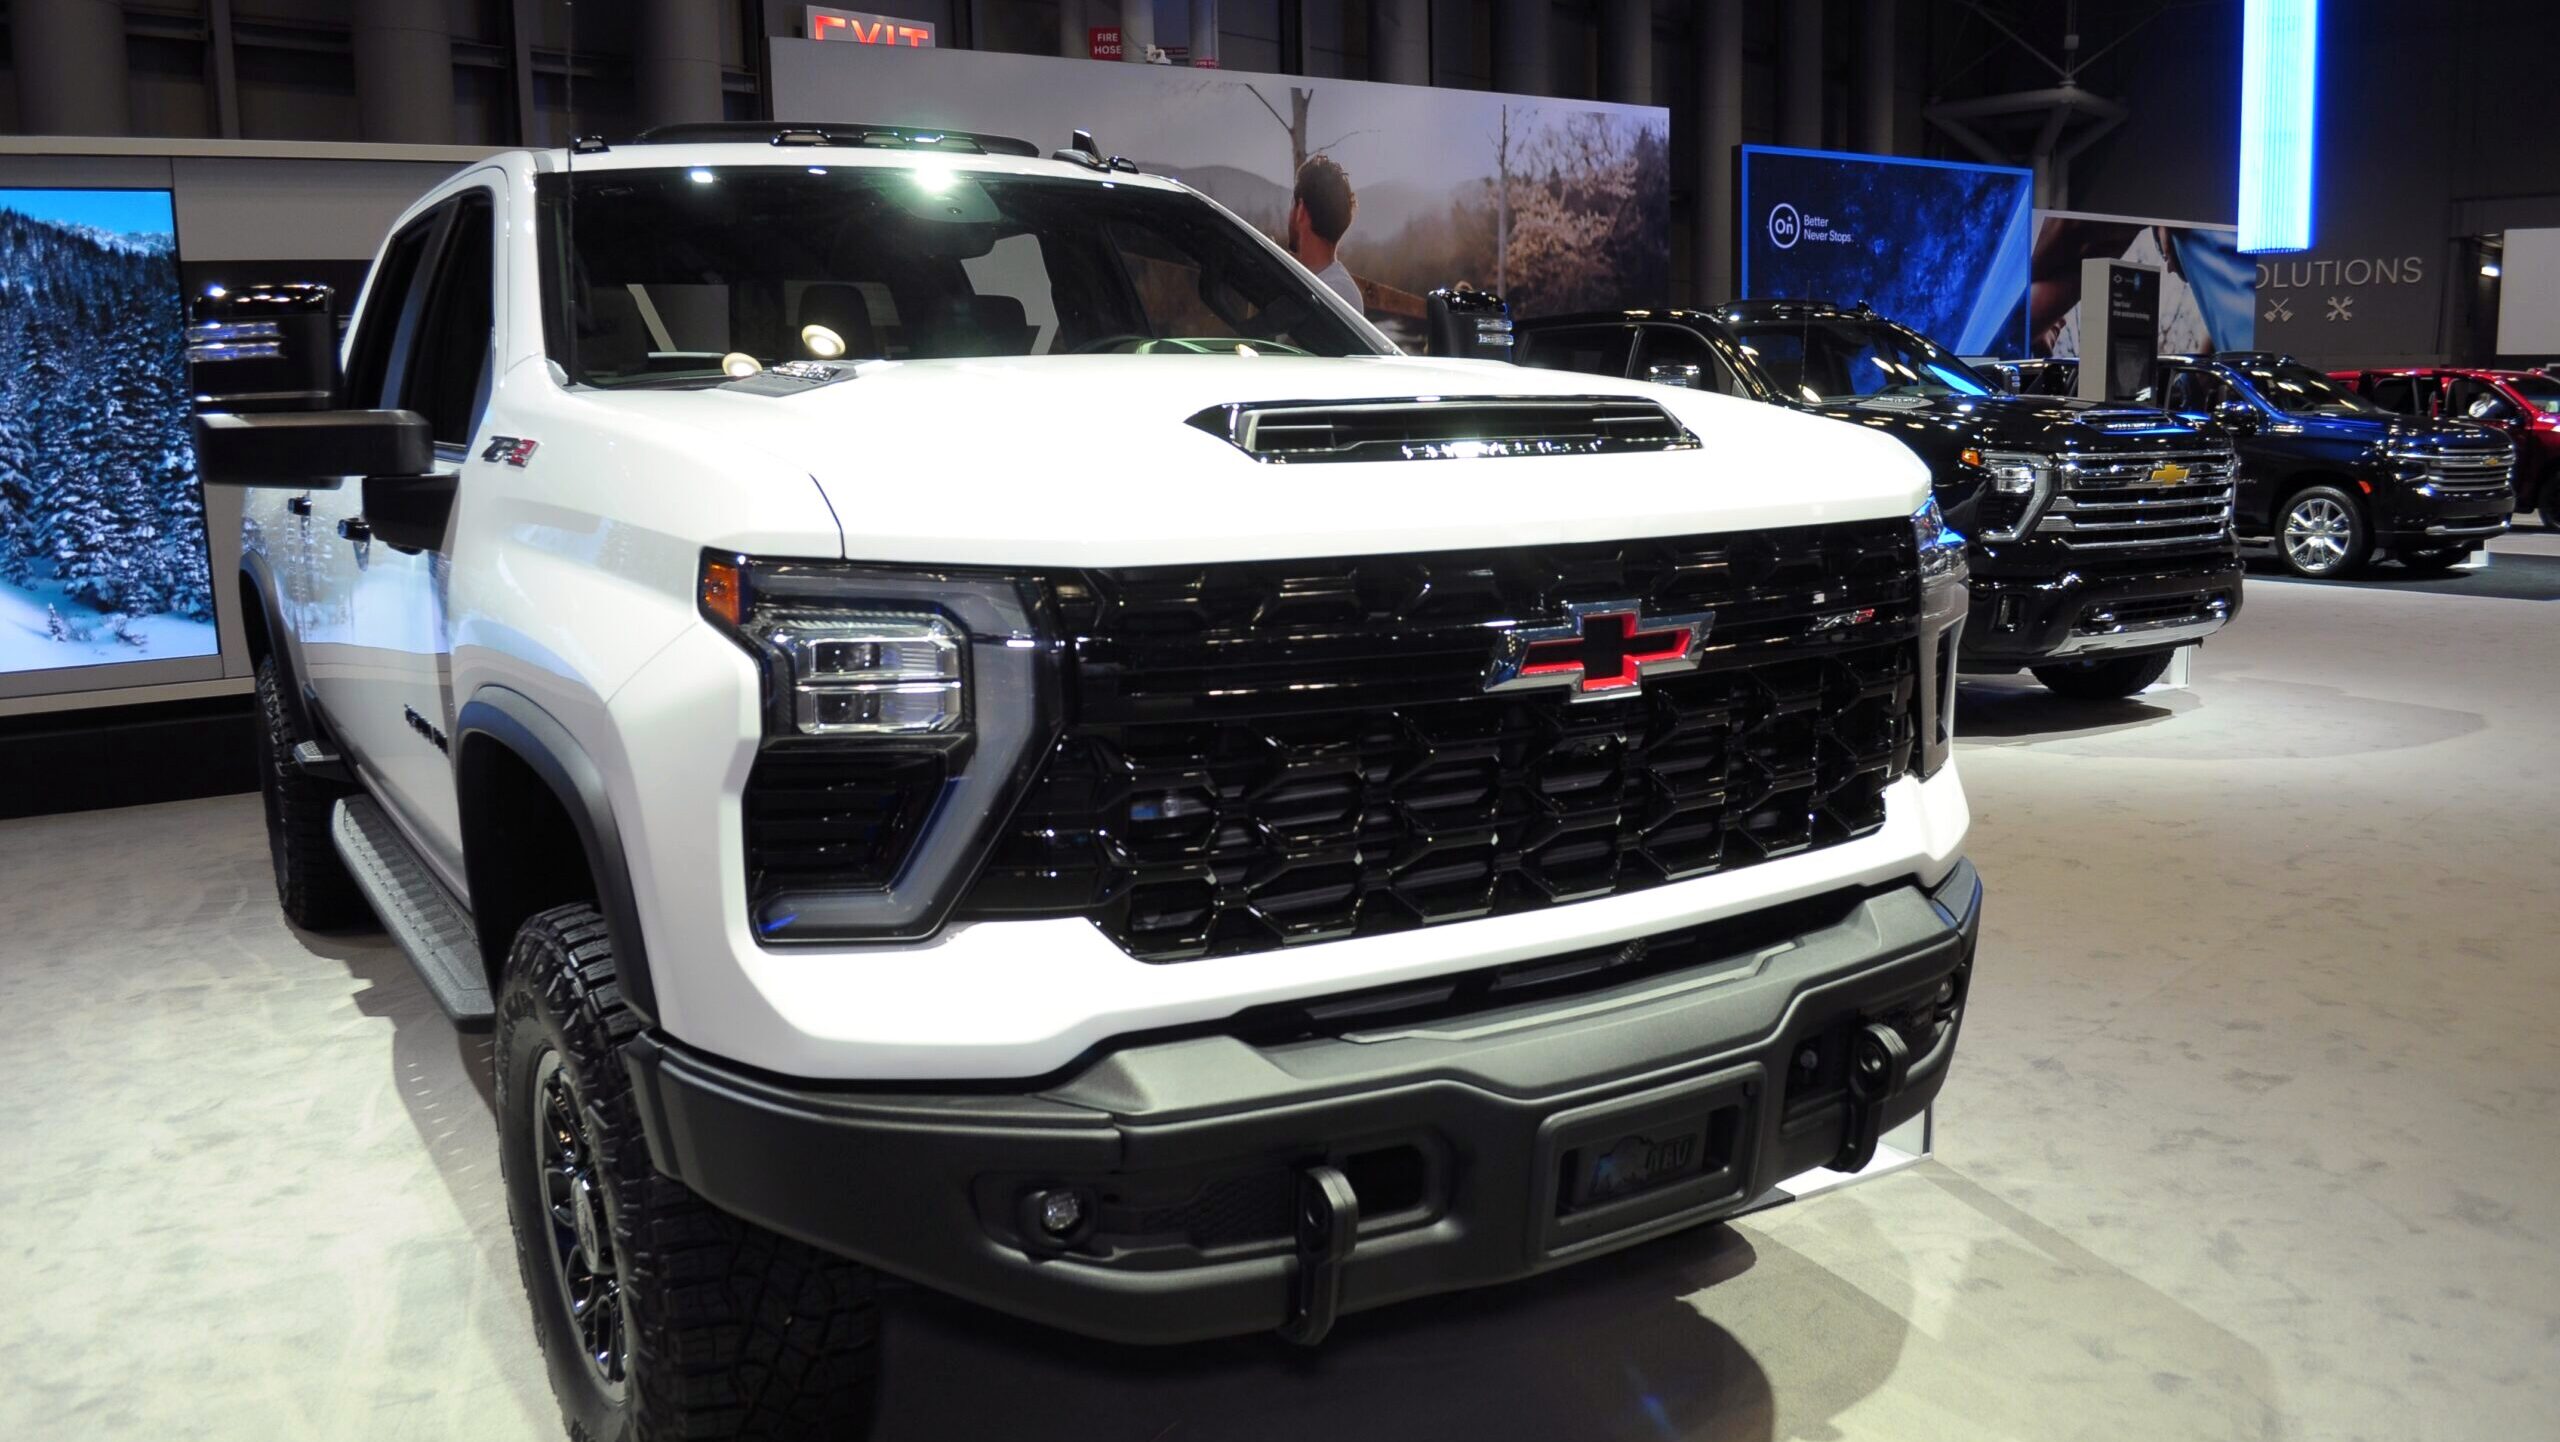
General Motors pulls up tomorrow to release its third-quarter results and will try to extend a streak of 16 consecutive earnings per share beats, according to Zacks Investment Research.
The streak could face a real challenge. GM already reported third-quarter sales volumes earlier this month, revealing deliveries fell at a 5.5% annualized rate to 670,974 vehicles in the three months ended Sept. 30. But expectations aren’t sky-high, with Wall Street eyeing flat revenue of $48.2 billion, according to Zacks. Worth watching will be a handful of forward-looking growth areas, including one that could challenge one of Tesla’s great ambitions.
Don’t Take the Wheel
Despite the softening sales, Cox Automotive analysts consider GM a shoo-in to retain its crown as the top-selling automaker in the country in 2026. Where GM has suffered most, like other US automakers, is fading electric vehicle (EV) sales after tax credits expired last year. In fact, in a testament to its core business, if you remove EVs from the third quarter delivery figures, GM’s sales were actually flat. The company was caught flat-footed earlier this year when consumers flocked to hybrid model vehicles in response to the energy price spike caused by the Iran war. Toyota reported a 29% increase in US hybrid sales, while GM was mostly left out of the action with just one single hybrid offering, a Corvette sports car. Executives say more hybrids are coming.
In any case, the Detroit mainstay has kept an ultradisciplined pricing strategy, holding incentives and discounts below industry averages in order to protect its margins. In a testament to this strategy, GM’s North American operations reported an 8.6% EBIT-adjusted margin in the second quarter, up from 6.1% a year earlier. As a result, profits have remained resilient: In the 12 trailing months ended June 30, GM reported a 1.1% dip in revenue to $185.5 billion, but a 9.7% increase in earnings before interest and taxes to $14.4 billion.
GM has also established several emerging avenues for long-term growth, and some are already bearing fruit. Take GM’s deferred revenue and services business, which has quietly grown into a multibillion-dollar force. Revenue at the highly profitable unit jumped nearly 50% year over year in the second quarter to $6.3 billion, driven by subscriptions to navigation and safety platform OnStar and hands-free driver-assistance software Super Cruise. An even more advanced driver-assistance platform is on the way:
- CEO Mary Barra reiterated last week that GM is on schedule to release “eyes-off, hands-off” self-driving technology by 2028. While there are autonomous commercial robotaxi services in more than a dozen US cities, there are no fully autonomous passenger vehicles for sale.
- The timeline could put the company in line with or even ahead of market leader Tesla, which is also racing to roll out autonomous driving technology that won’t require human supervision. Talk about Chevy Cruze control.
Buicking the Trend: GM has other medium-term irons in the fire: a joint venture with LG to mass produce battery cells and a defense unit angling to increase lucrative military contracts. Analysts are keeping the faith, with GM’s average Wall Street price target of $102.20 implying a 22% upside from Friday’s closing price.
Recent News
-

Photo illustration by Connor Lin / The Daily Upside, Photo by Chanakon Laorob via iStock